Costco’s September lineup just dropped, and shoppers are already talking

As retailers move into the fall selling season, warehouse chains typically use September to shift from late-summer staples to cooler-weather food, apparel and seasonal goods. Costco’s latest September lineup is now visible through its warehouse savings and monthly digital content, giving members an early look at what is being promoted nationally and what may still vary by store. The result is a broad but closely watched reset that combines scheduled discounts, seasonal merchandising and warehouse-by-warehouse variation.

Costco has launched its September lineup with a warehouse savings window running through Sept. 20

Costco has officially launched its current September lineup through its Warehouse Savings program, with the company stating on its website that the promotion is valid from August 24, 2026, through September 20, 2026. That gives the event a nearly four-week window across warehouses, although Costco also notes that pricing may vary by location in Alaska, Hawaii, Puerto Rico, Costco Business Centers and online. The company’s monthly digital content for September was also published on September 1, 2026, marking the start of the month’s broader merchandising push.

The posted savings show that food remains a major part of the September mix. Among the grocery offers listed by Costco are Chomps Original Beef Sticks, 12 count, Item 1532925, with a $5 discount; Dino Buddies Dinosaur-Shaped Chicken Breast Nuggets, 5 pounds, Item 1560758, priced at $10.99 after $4 off; and Alani Nu Energy Drink variety packs, 18 cans of 12 fluid ounces, Items 1833411 and 1937492, with $6 off. Costco also lists Go Raw Organic Sprouted Pumpkin Seeds, Sea Salt, 22 ounces, Item 1491866, with a $4 discount.

The same savings cycle also includes fall-weight apparel and home categories, underscoring that September at Costco is not limited to food. The company is advertising items including a Lucky Brand women’s V-neck sweater, Hilary Radley women’s crepe pull-on pants, a Weatherproof Vintage women’s flannel shirt and a 32 Degrees women’s fleece jacket. Those listings reflect the standard Costco seasonal transition, where grocery promotions run alongside apparel and household resets rather than as a stand-alone food event.

The immediate impact for shoppers is national, but exact in-store assortments remain local

For shoppers in the United States, the most immediate takeaway is that the September lineup is national in structure but local in execution. Costco’s own savings page says pricing may vary by location, and the company’s weekly warehouse materials separately note that some items may not be available in all locations. That means members in large markets such as Los Angeles, Chicago, Dallas, Phoenix or Atlanta may all be shopping the same promotional window without seeing identical shelves.

That store-level variation is also reflected in how Costco shoppers track inventory. A September 1, 2026 moderator post in the Costco subreddit directed users to include their approximate location or region because product availability can “greatly vary” and not all products are available nationwide. While that is not an official company inventory bulletin, it reflects the same limitation Costco states in its own promotional material: a published deal does not guarantee universal in-stock status at every warehouse.

Costco has not released a comprehensive city-by-city or state-by-state list of every September product placement. What is confirmed is the national savings period and the named items appearing in official warehouse promotions. What is not publicly known in a complete form is which individual warehouses received every promoted seasonal item first, or how deeply each store is stocked as September begins.

The September reset reflects Costco’s broader operating model and digital merchandising strategy

The reason Costco’s monthly lineups draw close attention is tied to how the company runs its business. In its 2025 annual report, Costco said its merchandise mix spans foods and sundries, non-foods, fresh foods and warehouse ancillary businesses, with e-commerce and digitally enabled sales playing a significant supporting role. The company reported that e-commerce represented about 7% of total net sales in 2025, while digitally enabled sales represented about 10%, showing how online merchandising now helps direct warehouse traffic as seasonal programs launch.

Costco also said in that filing that it seeks alternative sources or items when supply becomes unavailable and continues to diversify its supply chain and expand in-country production for future product needs. That helps explain why monthly lineups often combine recurring staples with rotating limited-time goods, and why exact availability can differ by market. The model is built around a relatively narrow assortment, fast inventory turns and the ability to swap products as demand and supply conditions change.

For customers, that means the practical expectation is straightforward. The national September promotion window is set, several headline grocery items and fall goods are already confirmed, and more warehouse-specific finds are likely to surface as stores complete their seasonal resets. Costco’s own materials indicate that the current warehouse savings cycle runs through September 20, 2026, giving members a defined timeline even as selection and pricing details continue to differ by location.
An urban farm built to fight food deserts is now feeding thousands at an NFL stadium

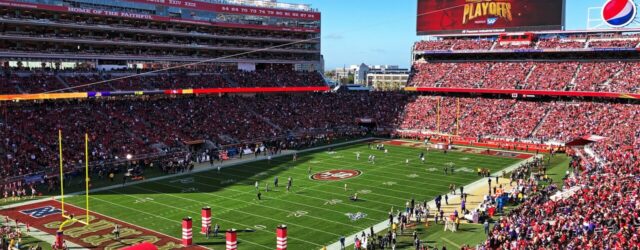
Levi's Stadium

As sports venues and food operators face growing pressure to cut waste and source more ingredients locally, stadium sustainability projects have become a bigger part of the live-events business. At Levi’s Stadium in Santa Clara, the San Francisco 49ers’ rooftop Faithful Farm has turned that broader trend into a working food-production site, with produce now helping feed fans at NFL games and supporting donations in the Bay Area. What began as a project tied to food access and community education has become one of the most visible examples of an urban farm integrated directly into a major U.S. stadium.

Levi’s Stadium put a working farm on its roof

Levi’s Stadium officially unveiled the Faithful Farm on September 14, 2016, saying the project brought the first rooftop farm to a professional sports venue, according to the stadium’s announcement. The farm was developed with California urban-farming company Farmscape and was described at launch as a way to create local jobs, educate the community and grow vegetables and herbs for use at the venue. The stadium said the installation was designed as a working agricultural space, not a symbolic garden.

The scale has grown into a meaningful part of stadium food operations. In the San Francisco 49ers’ 2025 media guide, the team said the 7,500-square-foot rooftop farm supports more than 40 organic rotational crops, including tomatoes, squash, peppers and eggplants. The same team document said the annual yield exceeds 10,000 pounds and that all of the harvest is used in dishes served at Levi’s Stadium, with excess produce contributing to humanitarian efforts through food banks and nonprofits across the Bay Area.

That output is why the project now reaches far beyond a single premium amenity or sustainability display. A farm producing more than 10,000 pounds a year can feed large event crowds over time while also sending surplus into community distribution channels. The 49ers have not published a game-by-game breakdown showing exactly how many menu items use Faithful Farm produce or how much is donated each season, but the team has confirmed both uses publicly.

The local impact is centered in Santa Clara and the Bay Area

The confirmed geography is narrow and specific: the farm sits on the roof of Levi’s Stadium in Santa Clara, and the produce is used at the 49ers’ home venue and directed to Bay Area nonprofits when there is excess harvest, according to the 49ers’ media guide. That makes the local impact distinct from national stadium-sourcing programs that rely on distant distributors. In this case, food is being grown and consumed, or redistributed, within the same regional economy.

The food-access mission is also part of the project’s original framing. When Levi’s Stadium announced the farm in 2016, the venue said the project would provide community education on growing food close to home while also producing ingredients for stadium kitchens. That message aligned with a broader Bay Area conversation around food access, neighborhood-level production and reducing the distance between farms and consumers.

What is not publicly clear is the exact share of the harvest that goes to concessions versus community partners in any given year. The 49ers have said excess produce supports food banks and nonprofits, but they have not released a comprehensive annual breakdown naming every recipient organization or listing pound-by-pound allocations. Even so, the team has consistently described the farm as part of both its food-service system and its community-support efforts in the region.

The project reflects broader pressures on stadium food and food access

The reason this kind of project exists is tied to multiple documented trends. Stadium operators have spent the past decade looking for ways to reduce food miles, improve sustainability credentials and differentiate their food programs, according to Levi’s Stadium materials and industry coverage of the venue. Levi’s Stadium has repeatedly highlighted local sourcing in its food operation, and an NRDC report previously said 85 percent of ingredients and products used there were sourced within California, with 70 percent of food suppliers located within 150 miles of Santa Clara.

The food-desert connection comes from the wider urban-agriculture movement that treats local growing as both an access issue and an economic-development tool. At the Faithful Farm’s unveiling, Levi’s Stadium said the space would educate residents about what can be grown close to where people live while creating jobs and supplying fresh food. Farmscape and later business coverage have continued to present the site as a model for producing food inside dense developed environments rather than relying entirely on traditional farmland.

For customers and residents, the practical takeaway is straightforward. Fans at Levi’s Stadium can expect some produce used in stadium dishes to come from the venue’s own roof, while surplus harvest continues to support Bay Area food banks and nonprofit partners, according to the 49ers. As Levi’s Stadium keeps hosting large-scale events beyond NFL games, including its recent run of major international matches, the farm remains a fixed part of how the venue links food service, sustainability and local community support.

This Arizona Mexican restaurant survived 30 years, so why is it closing its doors now?

Restaurant closures have continued to reshape local dining districts across the U.S., with independent operators facing pressure from higher operating costs, seasonal swings and redevelopment around long-established corridors. In Scottsdale, that trend has now reached Old Town Tortilla Factory, a restaurant that spent about 30 years serving Southwestern fare with a Mexican influence from a historic adobe property on East Main Street. The business announced July 31, 2026, that it was closing permanently after three decades in operation.

A 30-year Scottsdale restaurant has shut down

Old Town Tortilla Factory confirmed in a public farewell message on July 31 that it had “decided to close after three decades of serving Scottsdale,” according to the restaurant’s own statement as reported by Arizona’s Family and Mouth by Southwest. Arizona’s Family reported the restaurant was located at 6910 E. Main St. in Scottsdale and said management described the closure as the end of an era. Mouth by Southwest reported the restaurant originally opened in 1996, putting its run at roughly 30 years.

The scale of the closure is limited to one confirmed restaurant location in Scottsdale based on the available reporting. No broader multi-unit shutdown has been publicly announced, and no company filing or chainwide restructuring has been tied to the restaurant. That makes this a single-site closure, but one with an outsized profile in Old Town because of how long the restaurant had operated in the district.

Coverage from Arizona’s Family and other local outlets described the restaurant as a longtime destination for celebrations, family dinners and private events. Mouth by Southwest reported that its distinguishing features included a 1,400-square-foot flagstone patio and a bar program with more than 120 tequilas. Those details help explain why the closure drew attention beyond a routine restaurant turnover.

What is confirmed in Scottsdale, and what is still unknown

What is confirmed is narrow and specific: the Scottsdale restaurant has closed, and the announcement came from the business itself on July 31. Arizona’s Family said the restaurant posted the news on its website and social media, while Mouth by Southwest reported that the final closure message arrived just days before a previously announced summer reopening. That timeline matters because the restaurant had signaled on June 28 that it would close from June 30 through August 2 and return on August 3, according to Mouth by Southwest.

That means customers in Scottsdale lost a restaurant that, until late June, appeared to be taking a normal seasonal break rather than preparing for a permanent shutdown. The closure affects Old Town Scottsdale specifically, and the confirmed address places the property in the city’s established dining and arts corridor. No other Arizona city has been identified as affected because no additional locations were publicly connected to the business.

Several details remain unconfirmed. The company has not released a fuller explanation for the shutdown, has not publicly identified whether the property will house a new operator, and has not outlined whether staff were transferred, retained or laid off. Mouth by Southwest reported that efforts to reach the Flaum family for comment were unsuccessful, and Arizona’s Family said no additional details were provided about what may replace the restaurant.

The unanswered question is why it closed now

The clearest answer so far is that the owners decided to close, but they have not publicly stated why. The restaurant’s farewell message, as quoted by Arizona’s Family and Mouth by Southwest, thanked customers and said to “stay tuned for what is next,” indicating the story of the property may continue even if the restaurant will not. Neither outlet reported a bankruptcy filing, lease dispute, sale announcement or other official cause tied to the decision.

Mouth by Southwest added the most important piece of context: something appears to have changed between the June 28 summer-break notice and the July 31 permanent-closure announcement, but “what changed in the month between those two posts hasn’t been explained publicly.” That leaves the central question unresolved on the record. In practical terms, Scottsdale diners should treat the closure as permanent while watching for any future announcement tied to the Main Street property.

For residents and visitors, the immediate effect is straightforward. Old Town Scottsdale has lost one of its longest-running Mexican and Southwestern dining destinations, and there is no public reopening plan for the restaurant under its current name. The last official word from management was its July 31 statement signaling that something else may come next at the site, but no successor concept has yet been publicly identified.

After 80 Years, This Texas Favorite Just Served Its Last Meal

Independent restaurants across the country have faced years of pressure from higher food costs, labor expenses, and post-pandemic operating changes. In Houston, that pressure has now claimed one of the city’s longest-running restaurants. Barbecue Inn, the family-owned institution on West Crosstimbers, served its last meal on August 1, 2026, ending an 80-year run.

Barbecue Inn closed after dinner service on August 1

Barbecue Inn, the Houston restaurant founded in 1946, closed after dinner service on Saturday, August 1, according to reporting by the Houston Chronicle and ABC13. The closure ended roughly eight decades of continuous operation for a business that had remained in the Skrehot family for three generations. Local coverage identified the restaurant as one of Houston’s most recognizable legacy dining rooms, known as much for its fried chicken and seafood as for the barbecue in its name.

The restaurant operated at 116 West Crosstimbers Street and had become a fixture for generations of diners in north Houston. Houstonia reported that customers lined up in the final days after the family announced the restaurant would close that weekend. The Houston Chronicle described the closing as the end of an era for Oak Forest and nearby neighborhoods that had treated the restaurant as a longstanding family destination.

ABC13 reported that owner Wayne Skrehot said he was closing the business as he retired. Coverage from multiple local outlets said the restaurant’s first menu dates to 1946, shortly after Louis and Nell Skrehot converted a small house into the original operation. That history made Barbecue Inn not just an old restaurant, but one of the city’s enduring family-run food businesses.

Houston is losing a long-running neighborhood institution

The confirmed closure is specific to Houston, where Barbecue Inn had operated for its full lifespan. Reporting places the restaurant in the Oak Forest and Independence Heights area, and local outlets consistently tied the loss to north Houston’s neighborhood dining culture. No other Texas locations were involved, and there is no indication that the business operated as a chain elsewhere in the state.

What is confirmed is that the Houston restaurant has closed permanently. What is not publicly confirmed is any broader plan for the property, including whether another restaurant will take over the site or whether any family-led revival is possible. The owners have not released a broader redevelopment plan, and no public list of related closures exists because Barbecue Inn operated as a single location.

The local impact also lands during a period of unusual turnover in Houston’s restaurant scene. Houstonia reported that other established local restaurants, including Istanbul Grill, Paulie’s, and Rudi Lechner’s, have also closed recently, while Picos was preparing to close later in 2026. In that context, Barbecue Inn’s final service stands out not because of a statewide footprint, but because one Houston address carried 80 years of family and neighborhood history.

Retirement and rising costs drove the decision

The reasons cited for the closure were direct. ABC13 reported that Wayne Skrehot said he was retiring, while the Houston Chronicle and Houstonia both said the family also pointed to rising operating costs. According to those reports, the economics of running the restaurant had become increasingly difficult in the years following the COVID-19 pandemic, as food and other business expenses climbed.

That explanation fits a broader pattern affecting older independent restaurants, especially businesses operating in large legacy spaces with labor-intensive service models. Barbecue Inn was known for a traditional full-service format and made-to-order comfort food, a model that can be harder to sustain when ingredient, wage, and overhead costs rise. Local reporting did not cite a single triggering event such as a sale, bankruptcy filing, or disaster; instead, the closure was framed as a retirement decision shaped by long-term financial pressure.

For customers, the practical reality is simple: the restaurant has already served its final meal, and no reopening has been announced. The company has not stated that another location will continue the brand, and no successor operation has been publicly identified. For now, August 1, 2026, stands as the confirmed final day for one of Houston’s best-known family restaurants.

Why This Common Ingredient in US Milk Is Banned Abroad

Milk looks simple on the shelf, but the politics behind it are anything but. One of the biggest controversies in modern dairy is tied to a substance many consumers never see on the label. And despite years of debate, the U.S. and several foreign governments still treat it very differently.

The ingredient is really a hormone used on cows, not in the carton

The ingredient often described in headlines as being “in U.S. milk” is recombinant bovine somatotropin, or rBST, also called rBGH. It is a synthetic version of a naturally occurring bovine growth hormone, and the FDA says it is approved in the United States to increase milk production in dairy cows. In other words, farmers do not add it to bottled milk; they inject it into lactating cows so the animals produce more milk over time.

That distinction matters because the public debate often confuses farm practice with food formulation. The FDA has long maintained that milk from treated and untreated cows shows no significant compositional difference relevant to human safety. That position helped keep rBST legal in the U.S. after the agency approved a commercial formulation in 1993.

Even so, the issue never disappeared, because other countries reviewed the same broad subject and reached different policy conclusions. Canada, for example, has said available research did not demonstrate a threat to human health from products of treated animals, yet it still did not approve rBST for dairy use. That decision signaled that the controversy extended beyond the contents of the milk itself.

Why Europe and Canada drew a harder line

The European Union’s permanent ban, formalized in 1999, was driven mainly by animal welfare concerns rather than a straightforward finding that the milk was unsafe for people. EU authorities concluded that using BST to push milk output increased stress on dairy cows and was associated with more mastitis, foot problems, injection-site reactions, and other painful conditions. In the EU’s view, that made the practice incompatible with acceptable standards for farm-animal welfare.

Canada’s position followed a similar logic. Health Canada has said the human food safety evidence did not show a clear danger, but regulators did not approve rBST because of concerns tied to animal health and management. That nuance is often lost when consumers hear that an ingredient is “banned abroad,” as if foreign regulators had found contaminated milk on store shelves.

In reality, the split reflects different regulatory values as much as different scientific judgments. U.S. regulators focused on whether milk from treated cows was materially different or unsafe for consumers. European regulators, by contrast, weighed the welfare cost to the animal much more heavily and decided the productivity gains were not worth it.

Why the issue still resonates with shoppers today

rBST remains legal in the United States, but market forces have sharply reduced its visibility. Many major milk brands now emphasize that their products come from cows not treated with artificial growth hormones, and USDA organic rules prohibit growth hormones in organic dairy production. So while the practice is still allowed under U.S. law, much of the retail milk case has already moved in a different direction.

That shift helps explain why the topic keeps resurfacing. Consumers increasingly want food systems that reflect not just safety, but also transparency, animal welfare, and production ethics. A practice can survive a regulatory review and still lose in the court of public opinion, especially when shoppers feel they were never clearly told what it was.

So the real story is less about a mystery additive in milk than about how nations define acceptable agriculture. The U.S. permits rBST because federal regulators concluded the milk is safe. Many countries abroad rejected it because they judged the effect on cows to be too high a price for extra production.

What the CDC Says the Average American Really Weighs

If you have ever wondered how your weight compares with the rest of the country, the latest federal data offers a measured answer. The Centers for Disease Control and Prevention, through its National Center for Health Statistics, has published the most recent national body-measurement snapshot for U.S. adults. That survey shows the average adult man weighs 199.0 pounds, while the average adult woman weighs 171.8 pounds.

CDC releases the latest measured national averages

The figures come from the National Health and Nutrition Examination Survey, or NHANES, which measures people in person rather than relying on self-reported answers. According to the CDC’s FastStats page and the NCHS anthropometric reference tables released in June 2025, the averages apply to adults age 20 and older during the August 2021 through August 2023 survey cycle. The same data shows the average adult man was 68.9 inches tall, or just under 5 feet 9 inches, and the average adult woman was 63.5 inches tall, or 5 feet 3.5 inches.

The CDC also reported average waist circumference alongside weight and height. For men, the average waist measured 103.0 centimeters, or about 40.6 inches, while for women it was 97.9 centimeters, or about 38.5 inches. Pregnant women were excluded from the weight, body mass index, and circumference tabulations, according to the federal report.

Because NHANES uses physical examinations, the dataset is considered one of the government’s most reliable sources for national body measurements. At the same time, the survey reflects a specific period, not a real-time national count. That means these numbers describe the country during a defined two-year window rather than what every American weighs today.

What the data shows — and what it does not

This is national data, not a state-by-state ranking, so the CDC report does not identify average weight by city, county, or individual state in the release tied to these headline figures. It also does not say what a healthy weight should be for any one person. Federal researchers present the numbers as population averages, not personal health targets.

The broader context is that many U.S. adults fall into the federal categories for overweight or obesity. In February 2026, the CDC reported that 40.3% of adults age 20 and older had obesity during the August 2021 through August 2023 period, while another 32.1% were classified as overweight. Combined, that means roughly 72% of adults fell into one of those two categories under standard body mass index definitions.

The obesity pattern was not uniform across age groups. According to an NCHS data brief, obesity prevalence reached 46.4% among adults ages 40 to 59, compared with 35.5% for adults ages 20 to 39 and 38.9% for adults age 60 and older. The agency also reported lower obesity prevalence among adults with a bachelor’s degree or more than among adults with less education.

Why these averages matter in the broader health picture

The long-term trend helps explain why the headline figures stand out. CDC historical obesity data shows the prevalence of obesity has risen sharply since the early 1960s, even though the most recent comparison did not show a statistically significant jump from the prior survey cycle. In its February 2026 update, the agency said changes between 2017 through March 2020 and August 2021 through August 2023 were not statistically significant for overall adult obesity prevalence.

Even so, severe obesity continued to command attention in the federal data. The CDC reported an age-adjusted severe obesity prevalence of 9.7% in August 2021 through August 2023, with a crude estimate of 9.4%. That means nearly 1 in 10 U.S. adults met the standard definition of severe obesity based on body mass index.

For readers, the practical takeaway is that the national average is a snapshot, not a prescription. The CDC notes that BMI does not measure body fat directly and does not show how fat is distributed in the body, which is why clinicians often consider waist circumference, medical history, and other indicators alongside weight. For now, the latest measured federal benchmark remains straightforward: about 199 pounds for the average U.S. man and about 172 pounds for the average U.S. woman.

What College Football Season Means for Beer Sales

College football season arrives at a pivotal moment for the U.S. beer business, which has been balancing softer overall alcohol demand with strong event-driven spikes. As campuses, bars and retailers gear up for Saturdays, the season still represents a reliable volume driver for stadium vendors, wholesalers and brands tied to game-day drinking. Recent industry and college athletics data show that football remains one of the clearest occasions for beer sales to accelerate in the fall.

College football remains a proven sales event for beer

The most visible recent sign came on August 27, 2025, when Army announced it would begin selling alcoholic beverages at football games at Michie Stadium, leaving no service academy outside the trend, according to The Associated Press. AP also reported in 2023 that 55 of 69 Power Five schools and Notre Dame were already selling alcohol in public areas of their stadiums on game days, underscoring how widespread in-stadium beer sales have become in major college football. That shift matters because it turns game day into a direct revenue channel for athletic departments as well as for beer suppliers.

Schools and licensing partners are also finding incremental revenue in team-branded beer. AP reported that Learfield said college-licensed alcoholic beverages generated $7.5 million in total sales during fiscal 2024, while Tennessee officials said Vol Lager ranked among the top four beers sold at Neyland Stadium last fall. Those numbers show that the football season now supports both concession sales and retail beer programs tied to campus brands.

The broader beer supply chain treats football as a material selling season. The National Beer Wholesalers Association said Super Bowl demand drives beer sales about 20% above average nationally, with Americans spending $1.3 billion on beer in the two weeks leading up to the game and another $1 billion on game day. While that figure reflects the NFL rather than college football, it illustrates the scale that live football viewing can create for brewers, distributors and retailers.

The local impact is clearest around stadium districts and sports bars

In college towns and metro areas anchored by major programs, beer demand tends to spread beyond the stadium itself. Tailgates, campus bars, chain restaurants and neighborhood taverns all participate in the same weekend traffic cycle, especially where schools now sell beer both inside venues and through licensed retail partnerships. AP reported that at North Carolina, alcohol sales produced about $4 million, after net sales of $320,213 in the 2019-20 athletic year rose roughly fourfold by the following year cited in the report.

Even so, the exact distribution of those gains is uneven and often not publicly broken out by city, venue type or state. Colleges generally do not release a comprehensive public accounting of how much beer is sold at each concession stand, and beer companies rarely disclose college-football-specific weekly sell-through by campus market. What is confirmed is that many fans still split their spending between lower-cost tailgating outside and higher-margin purchases inside the stadium, a pattern AP documented in fan interviews and school reporting.

For on-premise operators, sports-driven occasions are increasingly important because draft remains a high-volume format in bars and restaurants. CGA by NIQ and Draftline Technologies said draft beer accounted for 52.3% of total beer sales by volume in U.S. bars and restaurants in the year to early 2025, with especially sharp outlet growth in neighborhood bars, sports bars and casual dining. That makes football weekends especially relevant for operators built around televisions, taps and game-day traffic.

Football matters more because beer needs dependable demand spikes

The importance of college football is sharper because the beer category is competing in a tougher market than it was a decade ago. CGA by NIQ reported that beer attracted 39.5% of all beverage alcohol sales by value in the U.S. on-premise in the 12 months to mid-June 2025, down 0.3 percentage points from a year earlier, while spirits and ready-to-drink products gained share. The same report said imported and domestic super-premium beer brands posted gains, while craft and domestic premium lost share.

Industry groups also continue to frame beer as a major economic engine even amid slower category growth. The NBWA’s 2025 Beer Serves America figures put the total U.S. beer industry’s economic impact at $56.1 billion and employment tied to the sector at 134,543 jobs in distribution alone across brewing, retail, agriculture and manufacturing links. That scale helps explain why dependable fall occasions such as college football still matter so much to local wholesalers and retailers.

For customers, that usually means wider beer assortments on game days, more stadium availability than in past seasons and continued marketing around school-branded or local labels. It does not necessarily mean uniform pricing or identical offerings from one campus or state to another, and many schools still have different rules on where alcohol can be sold. What is clear from recent AP and industry reporting is that beer has become a standard part of the college football business model, even as the category works to hold share in a more competitive drinks market.

The Froot Loops You’re Eating Aren’t Sold in Canada. Here’s Why

Froot Loops

Same mascot, same bright box, same sweet crunch. But the Froot Loops in an American pantry are not the same product Canadians pour into their bowls.

That difference comes down to ingredients, regulation, and years of pressure over what gives food its color.

The ingredient lists tell the real story

If you compare the two products side by side, the biggest difference is the source of color. WK Kellogg’s Canadian Froot Loops are marketed as having no artificial colours, and the ingredient list includes coloring from concentrated carrot juice, anthocyanin, annatto, turmeric, concentrated watermelon juice, concentrated blueberry juice, and concentrated huito juice. In the United States, WK Kellogg’s current ingredient list still includes synthetic color additives such as Red 40, Yellow 5, Blue 1, and Yellow 6.

That is why consumers often notice a gap between the two boxes even when the branding looks nearly identical. Canadian Froot Loops are built around plant- and fruit-derived coloring systems, while U.S. Froot Loops continue to use the vivid petroleum-derived dyes that have long defined the cereal’s look on American shelves.

There are other formulation differences too. The U.S. product listing also shows BHT for freshness on some labels, while the Canadian version emphasizes natural flavours and a different overall ingredient profile. These are not accidental variations. They reflect deliberate market-specific recipes created by the same parent company for different regulatory and consumer environments.

Canada’s rules and market pressures pushed a different formula

This does not mean synthetic dyes are outright banned across Canada. Health Canada maintains a list of permitted food colours and allows additives if they meet safety standards. But the Canadian system still creates a different commercial environment, one where companies often choose simpler-sounding labels and reformulate products to better align with retailer expectations, public health scrutiny, and consumer demand.

In practice, that has helped produce a cereal aisle where American-style dye-heavy formulations are less common in flagship products marketed to children. Companies selling in Canada know shoppers increasingly notice claims like “no artificial colours,” and that pressure shapes recipes as much as regulation does. The result is a softer but still powerful incentive to use juice- and spice-based coloring instead of synthetic dyes.

The contrast has become more visible as debate over food dyes has intensified in the United States. According to reporting from the Associated Press in 2024, activists specifically pointed to Canada’s version of Froot Loops as evidence that a major cereal maker already knows how to produce a naturally colored alternative. That comparison has turned one cereal box into a broader symbol in the fight over how processed foods are made.

The U.S. version may change, but not yet on most shelves

WK Kellogg has publicly said it is accelerating plans to eliminate artificial colors from its full cereal portfolio by the end of 2026, with updated recipes including Froot Loops beginning production in 2026 and shipping to retailers before year-end. That means the American formula is expected to move closer to what Canadian consumers have already been buying, but the transition is still underway.

For now, most U.S. shoppers are still eating the version colored with Red 40, Yellow 5, Blue 1, and Yellow 6. So when people ask why Canada gets a different Froot Loops, the answer is not that the cereal somehow changes at the border on its own. It is that manufacturers respond to different policy frameworks, public expectations, and market incentives in each country.

The larger lesson is that multinational food brands routinely tailor recipes by region. Froot Loops just makes that reality unusually easy to see because the product is famous for its colors. In this case, the rainbow in a Canadian bowl comes from fruit and vegetable concentrates, while the American one, at least for now, still comes from synthetic dye chemistry.

My Grandmother’s Depression-Era Meat Trick Still Works Wonders

A lot of kitchen wisdom survives because it solves real problems. My grandmother’s favorite meat trick did exactly that, and it still earns its place on the stove.

What looked like thrift was also technique. In many ways, modern cooks are only now catching up to what frugal home kitchens understood generations ago.

The old trick was never really about “cheapening” meat

During the Depression, home cooks learned to make a little meat go much further by mixing it with ingredients that added bulk, moisture, and nourishment. Breadcrumbs soaked in milk, crushed crackers, oats, rice, or beans were common additions, especially in meatloaf, patties, meatballs, and stews. Historical USDA household diet records show how heavily earlier American diets leaned on beans, grains, milk, and other modest staples when meat was scarce or expensive.

What my grandmother did was simple: she never treated ground meat as a stand-alone ingredient. She built it out with a panade, the classic mixture of starch and liquid that cooks now praise for improving texture. Food science writers at Serious Eats have explained that panades help ground meat retain moisture, limiting the tight, rubbery texture that happens when proteins seize during cooking.

That matters even more now because meat remains one of the most volatile items in the grocery cart. USDA Economic Research Service data showed beef and veal prices rose 5.4 percent in 2024, while USDA and Bureau of Labor Statistics updates in 2025 and 2026 continued to show tighter beef supplies and higher year-over-year beef prices. What once looked like necessity now looks like intelligent adaptation.

Why the method works so well in a modern kitchen

The genius of the trick is that it improves eating quality while lowering cost. When breadcrumbs or oats absorb milk, broth, or even grated onion, they create a soft matrix inside the meat mixture. As the meat cooks, that structure holds onto juices, giving you a loaf, burger, or meatball that tastes richer even though it contains less meat by weight.

This is why some of the best meatloaf recipes still rely on soaked bread rather than extra beef. The filler does not merely stretch the mixture; it protects tenderness. That same principle appears in cuisines around the world, from meatballs bound with bread to dumpling fillings extended with tofu, cabbage, or mushrooms. Grandmothers did not call it food science, but they understood the result every time they sliced into a juicy loaf.

There is also a nutrition argument for this approach. Adding lentils, beans, oats, or mushrooms increases fiber and can reduce the saturated fat per serving without making dinner feel skimpy. In a period when USDA says food-at-home prices are still rising overall, even if more slowly than the inflation spikes of 2022, that kind of practical flexibility is worth reviving.

How to use it without making dinner taste “stretched”

The key is proportion and purpose. For 1 pound of ground beef, turkey, or pork, a reliable starting point is 1/2 to 1 cup of soft breadcrumbs or quick oats plus about 1/2 cup of milk, stock, or another moistening ingredient. Let that sit for a few minutes before mixing so the starch hydrates fully instead of stealing moisture during cooking.

If you want a heartier version, replace part of the meat with finely chopped mushrooms, mashed beans, or cooked lentils. Mushrooms add savoriness, beans add creaminess, and lentils disappear especially well into tomato-based sauces or shepherd’s pie filling. The point is not to disguise the meat, but to support it with ingredients that make the final dish more balanced and more forgiving.

That is why the trick still feels modern. It answers today’s high beef prices, reduces waste, and often produces better texture than an all-meat mixture. My grandmother would have called that common sense. A lot of professional cooks would call it smart formulation, but the plate tells the same story either way.

Retail Theft Hit $45 Billion, and It’s Changing Fast

Retail theft is still a massive business problem. But the most repeated number in the debate has become a story of its own.

What looked like a straightforward surge in shoplifting is now a more complex mix of in-store theft, organized crime, fraud, and supply-chain attacks.

The $45 billion figure is real in one sense, but often misunderstood

The widely cited claim that retail theft hit roughly $45 billion has circulated through hearings, headlines, and industry briefings. Capital One Shopping recently estimated U.S. retailers lost about $44.2 billion to theft in 2024, putting the current discussion in that range. But that headline should not be confused with older claims that organized retail crime alone accounted for $45 billion a year. According to the National Retail Federation, that earlier organized-crime figure was incorrectly tied to its survey data and later retracted.

That distinction matters because “retail theft” is not one clean category. NRF’s long-running shrink surveys measure broad inventory loss, which can include external theft, employee theft, paperwork errors, vendor fraud, and other operational breakdowns. In its 2023 security survey, NRF said the average shrink rate for 2022 reached 1.6%, representing $112.1 billion in losses across the industry. Theft is a large part of that picture, but not the whole thing.

The result is a public argument shaped by overlapping numbers. Critics have pointed to the 2023 retraction as evidence that retail theft was overstated. Retailers, meanwhile, argue that even when one claim was corrected, the broader problem of theft and fraud never disappeared. Both points can be true at once.

The crime itself is evolving faster than many shoppers realize

Retail crime is no longer centered only on people stuffing merchandise into bags and running out the door. The FBI describes organized retail theft as large-scale stealing for resale, often crossing state lines and feeding broader criminal enterprises. NRF’s recent research says organized groups are increasingly using gift card fraud, phone scams, cargo theft, and supply-chain diversion alongside traditional store theft.

That shift helps explain why some retail executives say conditions feel worse even when shoplifting patterns begin to stabilize in certain places. NRF’s 2025 study found retailers saw an 18% increase in the average number of shoplifting incidents in 2024 versus 2023, along with a 17% rise in threats or acts of violence during theft events. Yet the group’s newer 2026 report also found average shoplifting incidents and merchandise theft incidents declined between 2024 and 2025, suggesting some store-level pressure may be easing.

What is not easing is the sophistication. Fraud taxonomies being developed by NRF and industry partners increasingly treat theft as part of a wider ecosystem that includes account takeover, return abuse, card fraud, and resale networks. In other words, the crime is moving from the aisle to the algorithm.

Retailers are changing their defenses, and policy is following

Retailers have responded with a mix of harder security and smarter analytics. Chains have added locked cases, receipt checks, product trackers, AI-assisted video review, and more targeted staffing around high-risk departments. According to NRF, some of the recent stabilization in store theft reflects years of investment in employee training and security technology rather than a clean resolution of the problem.

The downside is visible to shoppers. Everyday items such as toothpaste, baby formula, razors, and over-the-counter medicine are now more likely to sit behind barriers, especially in theft-prone urban stores. The FBI warns that organized retail theft can contribute to store closures, job losses, and even food or pharmacy deserts when merchants conclude a location is no longer viable.

Lawmakers are responding as well. NRF and law-enforcement advocates are backing the Combating Organized Retail Crime Act of 2025, which would create a stronger federal coordination structure for cases that stretch across jurisdictions and through online resale markets. The next phase of this fight will not be defined by one dramatic number. It will be defined by whether retailers and police can keep pace with a crime problem that is becoming less visible, more networked, and harder to measure.