A Major Food Company Is Cutting Jobs and Selling Off Its Washington Facility, Here’s What’s Going On

Tyson_Foods

The U.S. meat industry is continuing to reshape operations as cattle supplies stay tight and beef processors face higher livestock costs. Tyson Foods said on August 13 it will close two facilities and pursue the sale of its beef plant near Pasco, Washington, putting new attention on one of the Tri-Cities area’s longtime food employers. The Washington site is not scheduled for an immediate shutdown, but the company’s announcement adds uncertainty for workers as Tyson reduces its beef footprint.

Tyson confirmed a three-facility restructuring in its beef business

Tyson Foods announced on August 13 that it will end operations at its beef facility in Joslin, Illinois, close its beef and pork case-ready facility in Eagle Mountain, Utah, and pursue the sale of its Pasco, Washington, beef plant, according to the company’s press release filed with the Securities and Exchange Commission. Reuters reported the restructuring as Tyson moves to shrink its beef network during a prolonged cattle shortage.

The largest confirmed job impact is in Illinois. Tyson’s SEC filing said the Joslin closure affects about 2,500 team members, while Utah outlets, citing the state workforce agency, reported that 723 workers are affected at Eagle Mountain. Tyson has not publicly attached a Washington layoff total to the Pasco sale announcement in the same way it did for the Illinois closure.

Tyson said it plans to keep working with affected employees in Illinois, Utah, and Washington on opportunities at other company locations. Unlike the Joslin and Eagle Mountain sites, the Pasco-area operation is being marketed for sale rather than marked for an immediate end to operations, making its next phase dependent on whether a buyer is found.

The Washington impact centers on Tyson’s Pasco-area facility near Wallula

In Washington, the facility involved is Tyson Fresh Meats’ plant at 13983 Dodd Road in Wallula, just outside Pasco, according to Washington state facility records. Tyson and Reuters both identified the site as the company’s Pasco beef plant, a major processing operation that has long served the broader Tri-Cities economy.

What is confirmed so far is limited but significant. Tyson has said it is pursuing a sale of the Washington plant, not announcing an immediate closure, and Reuters reported that the company will continue helping Washington employees seek openings elsewhere in its network. As of now, there is no public Washington WARN notice cited in the available state database material tied to a mass layoff at the Pasco-area plant.

That means several details remain unconfirmed. Tyson has not released a comprehensive public count of Washington workers who could be affected if a sale does not go through, and it has not announced a buyer, a sale timeline, or a final operating date for the Wallula facility. For residents in Pasco, Wallula, Kennewick, and Richland, the practical reality is that the plant’s future remains tied to the outcome of a potential transaction.

Tyson ties the move to cattle shortages and deepening beef losses

Tyson has consistently pointed to industry conditions in its beef business. Reuters reported on August 13 that the company’s decision was driven by a historic U.S. cattle shortage that has deepened losses for the largest U.S. meatpacker. Earlier in August, Tyson said losses in beef were expected to widen, with a projected adjusted operating loss of $500 million to $650 million for fiscal 2026.

Company filings and earnings materials show the same pattern. Tyson’s quarterly report said its beef segment continues to face limited supplies of market-ready cattle and increased cattle costs, while its 2026 earnings commentary described those conditions as ongoing pressure on results. Those supply constraints have reduced profitability even as other Tyson business units performed better.

For customers and residents in Washington, the immediate takeaway is that Tyson has not said the Pasco-area plant will close now. The company’s stated plan is to pursue a sale while restructuring its broader beef operations, and no public buyer has been announced. Unless that changes, the most factual expectation is continued uncertainty around ownership rather than a confirmed shutdown date for the Washington facility.
Red Lobster Is Closing More Locations in a Move It’s Calling “Right-Sizing”

Restaurant chains across the U.S. are still trimming store counts as they confront high operating costs, uneven traffic, and the long aftereffects of pandemic-era debt and lease decisions. Red Lobster is the latest major casual-dining brand to keep shrinking, saying its newest closures are part of a deliberate effort to stabilize the business after its 2024 bankruptcy. The company’s latest move shows that even nationally recognized chains are still reducing footprints to focus on fewer, more profitable restaurants.

Red Lobster says the latest closures are part of a smaller-footprint strategy

Red Lobster has closed additional restaurants in recent weeks and now lists 484 U.S. locations, according to a September 8 report by Nation’s Restaurant News. That is 36 fewer than the 520 locations Technomic counted at the end of 2025, a decline of about 7% this year alone. The trade publication also reported that Red Lobster’s footprint is now roughly 25% smaller than it was at the end of 2023, before the chain began a wave of closures tied to its May 2024 Chapter 11 bankruptcy filing.

The company confirmed the strategy in a statement cited by Nation’s Restaurant News, saying the closures are part of a broader “right-sizing” effort rather than a one-time cutback. Red Lobster said reducing underperforming units will help fund restaurant refreshes and improve the guest experience at remaining stores. The company also described the move as part of a long-term growth plan rather than a retreat from the market.

Recent closures identified by local media and compiled by Nation’s Restaurant News include three restaurants in Alabama, two in Illinois, and one in California. Those reported closures followed other high-profile shutdowns this year, including a Columbus, Georgia, location that had operated for 55 years and a Times Square restaurant that closed in June after 23 years. Red Lobster has not published a single nationwide closure list tied to this latest round.

What is confirmed so far in affected cities, and what remains unclear

The most clearly confirmed recent closures are in Alabama, Illinois, and California, based on local reporting referenced by Nation’s Restaurant News. The company has not released a comprehensive city-by-city list for every restaurant affected in this latest “right-sizing” phase. That means customers in many markets may see reports of local closures before Red Lobster issues a broader public accounting of the changes.

What is known is the national scale. As of early September 2026, Red Lobster’s own website showed 484 U.S. locations, a figure cited by Nation’s Restaurant News after the latest closures were reflected online. That count provides the clearest snapshot of the chain’s current footprint, even as individual store shutdowns continue to emerge through local news reports and updated location pages.

For residents in states where closures have already been reported, the practical takeaway is that some long-running restaurants may disappear with little advance public notice. For customers elsewhere, nearby Red Lobster locations may remain open as the company concentrates spending on stores it believes can support future growth. Red Lobster has said it still expects new restaurants to be part of its future, with Chief Global Development Officer Kristen Briede saying in a July interview that new openings are anticipated eventually.

The company links the cuts to bankruptcy, leases, and underperforming stores

Red Lobster’s explanation for the continuing closures is rooted in problems the company and outside analysts have been discussing since last year’s bankruptcy. According to Nation’s Restaurant News, Red Lobster acknowledged in bankruptcy filings that it had overexpanded, a factor that contributed to sales and traffic problems. The chain has also been burdened by costly leases, a problem tied to the 2014 sale-leaseback of much of its real estate under former owner Golden Gate Capital.

Chief Executive Officer Damola Adamolekun has signaled for months that the company needed to get smaller before it could grow again. Reporting from Fortune earlier this year similarly described footprint reduction and cost control as central parts of the brand’s turnaround strategy. Red Lobster has paired the closures with efforts to improve operations, including restaurant remodels, service initiatives, and a revised version of Endless Shrimp intended to avoid the financial strain associated with the earlier promotion.

For customers, the immediate effect is a leaner chain with fewer locations but a stated focus on better-performing restaurants. Red Lobster said earlier this year that it was tracking ahead of its internal revenue and earnings forecasts, according to Nation’s Restaurant News, though the company has not publicly detailed the precise effect of each turnaround measure. Its current message is that additional pruning is meant to put the business on firmer long-term footing while it invests in the restaurants that remain.

This Qdoba Franchisee Just Defaulted on a $20 Million Loan, What Comes Next?

Qdoba

Restaurant financing pressures have become a growing issue across the quick-service and fast-casual business as operators juggle higher labor, occupancy, and tax costs. That pressure is now hitting one of Qdoba’s larger franchise groups in the Philadelphia area and beyond. Court filings and industry reporting show the dispute has moved from a loan default to court-supervised receivership, putting dozens of restaurants under added scrutiny.

A court-appointed receiver is now part of the case

Pennsylvania-based The Integritty Group, also identified in court records through related TIG Queso and Queso Time entities, defaulted on a $20 million loan that Bank Midwest said was taken out in April 2025. Nation’s Restaurant News reported on September 8, 2026, that about $18.3 million remained outstanding and that the debt was tied to 41 Qdoba restaurants. The lender had already filed suit on August 6 in the U.S. District Court for the Eastern District of Pennsylvania, according to that report.

The dispute escalated further on August 24, 2026, when a related federal case in Delaware resulted in an order granting the immediate appointment of a receiver. According to the District of Delaware docket, GlassRatner Advisory & Capital Group was appointed receiver over the borrower’s assets and business operations. That step typically means an independent party is installed to stabilize operations, protect collateral, and oversee a potential sale process rather than leaving those decisions solely with the borrower.

Bank Midwest said in the lawsuit, as summarized by Nation’s Restaurant News and the Kansas City Business Journal, that the franchisee violated loan terms, failed to cure the default, and did not disclose serious liquidity problems. The bank also said the franchisee entered an agreement to terminate its Qdoba franchise relationship and sell the restaurants without notifying the lender, which the bank said threatened the collateral behind the loan.

What is confirmed in Pennsylvania and what is still unclear

The most immediate local focus is Pennsylvania because The Integritty Group is based there and Qdoba said it remains focused on serving guests across the Philadelphia market. Nation’s Restaurant News reported that the companies named in the suit operate restaurants in Delaware, New Jersey, New York, Pennsylvania, and Florida. Court records viewed through Justia list multiple Pennsylvania entities among the defendants, but the public record cited in available reporting does not provide a complete store-by-store closure or sale list.

That means customers in the Philadelphia region should not assume a location is closing simply because it is tied to the franchisee. Qdoba said it is not a party to the complaint and has no comment on the allegations, while adding that it remains focused on serving guests in Philadelphia. As of now, no public filing reviewed in this reporting states that all 41 restaurants have shut down or that a final buyer has been selected.

What is known is that a receiver has been empowered to manage the restaurant assets and business operations. What is not yet known is which Pennsylvania locations, if any, could ultimately be sold, transferred, or restructured first. The company has not released a comprehensive list of affected Pennsylvania cities, and neither the court docket excerpts nor the trade reports publicly break out the 41-store portfolio by municipality.

Why the default matters and what customers should expect next

The filings point to a cash-flow problem more than a sudden one-day event. According to Nation’s Restaurant News, Bank Midwest said the franchisee owed roughly $432,000 in August rent on its Qdoba locations, more than $1 million in unpaid sales taxes, and more than $300,000 to DoorDash. The same report said the bank offered $850,000 in emergency funding to stabilize operations, but the franchisee never completed the paperwork needed to draw on those funds.

Those details fit a broader pattern in restaurant finance, where operators can remain open while falling behind on rent, taxes, vendors, and debt service until lenders or landlords intervene. In this case, the lender’s stated concern was that undisclosed liquidity strain and a possible franchise termination-and-sale arrangement could reduce the value of the collateral securing the loan. That is why the move to receivership matters more than the headline alone: it creates a formal process for oversight and a potential sale.

For customers, the near-term expectation is continued service where restaurants remain open, not an automatic systemwide shutdown. Any store transfers or sales would likely happen through the receiver and court process rather than through informal announcements alone. The case remains ongoing, and the clearest confirmed fact for now is that control over the 41-restaurant portfolio is moving into a more structured legal process.

General Mills Hiked Prices on Two Thirds of Its Products, So Why Did Customers Still Leave?

General Mills

Shoppers notice price before they notice brand messaging. And once a household changes its routine, winning it back is much harder than defending it in the first place.

Price hikes bought time, but they also changed behavior

For several years, General Mills relied on higher prices to protect profits as ingredient, packaging, labor, and freight costs climbed. That worked financially for a while, much as it did across packaged food, but it came with a tradeoff: unit sales weakened as shoppers became more price sensitive. Reuters reported that General Mills had been dealing with lower volumes as consumers pushed back on higher grocery bills and looked for cheaper alternatives.

The company’s own filings make clear why that matters. In its fiscal 2025 annual report, General Mills said it competes not only with large branded rivals but also with generic and private-label products that are generally sold at lower prices. It also warned that retailers can push for lower pricing, stronger promotions, and more reliance on store brands, all of which can pressure both volume and margins.

That pressure showed up in the numbers. General Mills said fourth-quarter fiscal 2025 net sales in North America Retail fell 10 percent to $2.6 billion, while full-year North America Retail sales fell 5 percent to $11.9 billion. Even though the company said investments in consumer value helped improve volume trends, the broader message was unmistakable: pricing power had limits, and shoppers were not infinitely loyal once the value gap widened.

Cutting prices later did not erase the earlier damage

General Mills eventually adjusted base prices across roughly two-thirds of its North America Retail portfolio, a move management framed as an effort to improve consumer value. Reuters said those cuts helped flatten volume declines, with reported volumes turning flat in one quarter versus a decline in the prior period. That was progress, but not a full recovery.

The reason is simple: shoppers had already learned new habits. Some moved to private label. Others shifted between channels, buying more from dollar stores, club stores, and discount-led retailers. Once consumers discover that a less expensive cereal bar, soup, or baking staple meets the need well enough, the branded product has to do more than merely trim price to win them back.

Retailers also gained leverage during that period. General Mills disclosed that Walmart accounted for 22 percent of consolidated net sales and 31 percent of North America Retail sales in fiscal 2025. When a giant customer is focused on sharper pricing, stronger promotions, and store-brand growth, a manufacturer cannot simply assume a rollback on shelf prices will automatically restore lost traffic or prior market share.

The bigger problem is that tastes changed while prices rose

Price was not the only issue. Demand in parts of the center store has been soft because consumer preferences have shifted toward products that feel fresher, healthier, or more aligned with high-protein eating habits. Reuters reported in March 2026 that General Mills was facing stiffer competition in protein-centric breakfast products as shoppers moved toward higher-protein options.

That matters especially for a company anchored in cereal, snacks, baking mixes, and pantry staples. A lower shelf price helps, but it does not fully solve a relevance problem. If a shopper now wants Greek yogurt, eggs, breakfast sandwiches, or a protein shake, a discounted box of legacy cereal may still lose.

General Mills understands this, which is why it has emphasized product news, reformulation, and innovation alongside pricing. In short, customers still left because the company was fighting on two fronts at once: repairing a value perception damaged by inflation-era price increases, while also adapting to a market where shoppers increasingly want something different from what the traditional packaged-food aisle has offered for decades.

Experts Say Trump’s New Beef Plan Won’t Actually Lower Your Burger Costs, Here’s Why

Beef Burger

Burger prices are painfully visible because they show up everywhere: grocery stores, fast-food menus, and backyard cookouts. That is exactly why any promise to make beef cheaper lands fast with consumers.

What Trump’s new beef plan actually does

President Trump’s latest beef action is not a broad attempt to lower all beef prices. It temporarily expands the U.S. tariff-rate quota for lean beef trimmings by 300,000 metric tons in 2026, with the added quantity released in three 30-day tranches beginning September 1, according to the Federal Register and White House fact sheets. The administration argues that the extra imported beef should be sold below current market prices and help relieve pressure on ground beef.

That sounds straightforward, but lean beef trimmings are only one part of the burger supply chain. They are commonly blended with fattier domestic beef to make the ground beef sold in stores and used by foodservice operators. So even if importers bring in cheaper lean trimmings, that does not automatically translate into a sharp drop in the retail price consumers see at the meat case or on a drive-thru board.

Reuters reported that economists and traders questioned whether the move would noticeably reduce prices because the import increase is relatively small compared with total U.S. beef consumption. Some countries also have not fully exhausted their existing quota access, which means the practical effect could be smaller than the headline number suggests. In other words, the policy is real, but its reach is narrower than the political message around it.

Why experts say burger prices are still likely to stay high

The biggest reason burger costs remain elevated is that cattle supplies are still tight. USDA’s latest cattle report put the July 1, 2026 inventory at 94.2 million head, with beef cows down 1% from a year earlier, and USDA has repeatedly said tight supplies are limiting production. The White House itself acknowledged that beef output is expected to fall around 4% from 2025 levels.

That supply squeeze has already shown up clearly in consumer prices. USDA’s Food Price Outlook says beef and veal prices in July 2026 were 9.4% higher than a year earlier, and the agency forecasts beef and veal prices will rise 9.8% for 2026 overall. When the underlying herd is small and production is falling, a temporary import adjustment is unlikely to overpower the broader market.

There is also a structural reason burger prices do not move in lockstep with raw cattle or import costs. USDA’s price-spread data notes that food prices are shaped not just by commodity costs, but also by labor, energy, processing, transportation, and distribution. A burger bought at retail or in a restaurant reflects all of those inputs, which means even modest relief on one ingredient can get diluted before it reaches the consumer.

The hidden math behind your burger bill

A burger is not just beef, and even the beef portion is not a simple pass-through from policy to checkout price. USDA previously estimated that a home-prepared 1/4-pound cheeseburger cost $2.40 in May 2025, with ground beef alone making up $1.50 of that total. That makes beef the biggest component, but still not the only one driving what families pay.

At restaurants, the disconnect is even bigger. Menu prices reflect rent, wages, packaging, utilities, franchise fees, and delivery costs alongside food ingredients. USDA’s latest food inflation data shows food-away-from-home prices in July 2026 were up 3.4% from a year earlier, even as month-to-month grocery inflation was flatter. So a cheaper imported trimming blend does not guarantee a cheaper combo meal.

The most likely outcome is modest, uneven relief for certain processors or buyers rather than a clear nationwide drop in burger prices. The administration may succeed in adding some supply to a strained market, especially for ground beef manufacturing. But unless the U.S. herd rebuilds meaningfully and broader production costs ease, experts are right to doubt that most shoppers will suddenly notice cheaper burgers at the store or on the menu.

A Beloved LA Cafe Just Filed for Chapter 11, Here’s What Happened

Marmalade Cafe

Restaurant bankruptcies have continued to hit regional chains as operators face higher labor, rent, and tax costs across California. In Los Angeles County and nearby communities, Marmalade Cafe has now joined that list after seeking Chapter 11 protection following a summer of location closures. The filing marks a major turn for a brand that has operated in Southern California since 1990.

Marmalade Cafe filed under Subchapter V after shrinking to four locations

Marmalade LLC, the company behind Marmalade Cafe, filed a voluntary Chapter 11 petition under Subchapter V on September 2 in the U.S. Bankruptcy Court for the Central District of California, according to court records and reporting by Nation’s Restaurant News. The filing came after the chain had already been reduced to four operating restaurants. Industry reporting said the company’s largest unsecured creditor is Gilmore Farmers Market, which is owed more than $481,000.

Nation’s Restaurant News also reported that Marmalade owes nearly $350,000 in state taxes. The same report said the chain had seven units at its peak but never expanded beyond Southern California despite receiving an investment from Parallel Investment Partners in 2007. The company did not immediately respond to requests for additional comment, according to that report.

Subchapter V is a part of Chapter 11 designed for smaller business reorganizations, allowing companies to continue operating while restructuring debt under court supervision. In this case, the filing does not mean the remaining Marmalade restaurants have shut down. Social media messaging cited by Nation’s Restaurant News said four Los Angeles-area units remain open during the bankruptcy process.

What the filing means in Los Angeles after Santa Monica and Calabasas closures

The clearest local impact so far is the loss of two Marmalade Cafe restaurants in August: one in Santa Monica and one in Calabasas. Nation’s Restaurant News reported both closures before the bankruptcy filing, and local coverage in Santa Monica and Calabasas separately confirmed the shutdowns. A Calabasas community report said the Commons at Calabasas location served the area for 28 years before its final day on August 2.

That leaves four confirmed Marmalade locations still operating in the Los Angeles region, with reports identifying Malibu, El Segundo, Sherman Oaks, and Westlake Village as the remaining restaurants. For diners, that means the brand has not disappeared from the market, but its footprint is now materially smaller than it was just weeks ago. The company has not released a broader public breakdown of future location plans beyond saying those four units remain open.

What is not yet known is whether any additional Southern California restaurants could close during the court process or whether leases, staffing, or vendor terms will be renegotiated. The company also has not released a comprehensive public statement explaining how the bankruptcy could affect employees or service at each remaining location. For now, the confirmed facts are the filing date, the August closures, and the continued operation of four sites.

The restructuring follows debt pressure and a difficult environment for regional operators

The documents and reporting available so far point first to debt obligations. Nation’s Restaurant News identified substantial unpaid obligations to a landlord creditor and to the state, giving a clearer picture of the financial pressures facing the company. Those balances do not, by themselves, explain every operational decision, but they show the scale of liabilities confronting the chain as it entered Chapter 11.

The broader context is also difficult for California restaurant operators. Across the industry, operators have been managing elevated food costs, wage pressure, occupancy expenses, and uneven customer traffic, especially for full-service concepts that rely on frequent neighborhood dining. Marmalade’s case fits that pattern in broad terms, though the company has not publicly attributed the filing to a single cause.

For customers in Los Angeles, the practical takeaway is that Marmalade Cafe is restructuring rather than liquidating at this stage. The four remaining restaurants are still open, according to the company’s public messaging cited by trade coverage, while the bankruptcy case moves through court. Any larger change to the chain’s footprint, ownership, or operations will likely emerge through future court filings or company statements rather than immediate storewide shutdowns.

Wendy’s just shook things up, but is Pizza Hut’s split from Yum the real winning move?

Wendy’s

Restaurant chains are making more structural changes as traffic softens and consumers become more selective about where they spend. This month, Wendy’s continued its executive reshuffle while Pizza Hut completed a corporate split that could reshape how one of the country’s largest pizza brands operates under new ownership.

Wendy’s adds a new growth executive as Pizza Hut’s sale closes

Wendy’s confirmed on August 24, 2026, that it appointed Tariq Hassan to the newly created role of chief marketing and customer growth officer, effective immediately. The company said Hassan, who previously served as chief marketing and customer experience officer for McDonald’s U.S., will report to President and CEO Bob Wright and join Wendy’s senior leadership team. The move came just over three months after Wendy’s announced Wright as president and chief executive officer on May 20, with the appointment effective May 21, according to the company.

That makes at least two major top-level changes at Wendy’s since late spring. The company framed Hassan’s hire as part of a broader effort to sharpen customer growth and brand positioning at a time when its latest earnings showed pressure on the business. In second-quarter results reported August 7, Wendy’s said global systemwide sales fell 6.5%, driven by an 8.2% decline in the U.S., while company-operated restaurant margin was pressured by commodity inflation, lower traffic, and labor rate inflation.

Pizza Hut’s shift was larger in scale. Yum Brands said on September 1, 2026, that it completed the sale of Pizza Hut outside Mainland China to LongRange Capital for about $1.5 billion, subject to adjustments, with a possible additional earn-out of $75 million by 2030. Yum said that transaction, combined with the August 7 closing of the Pizza Hut China sale to Yum China, completed the company’s previously announced $2.7 billion breakup of the brand into two separate deals.

What the changes mean in the U.S., and what is still unclear

For U.S. customers, the Wendy’s change is straightforward for now: it is a leadership move, not a confirmed menu, pricing, or store-count action. Wendy’s has not announced a national list of restaurant closures tied to the leadership reset, and the company has not said that Hassan’s appointment will immediately alter operations in any specific state or city. What is confirmed is that the hire gives Wright a new marketing leader as the chain tries to improve traffic and relevance in the domestic business.

Pizza Hut’s split could have broader operational consequences in the U.S., but several local details remain unknown. Yum said Pizza Hut outside Mainland China is now owned by LongRange Capital, and Nation’s Restaurant News described the deal as official, but neither company has publicly released a comprehensive state-by-state breakdown of how ownership or support functions may shift at the restaurant level. The companies also have not published a full list of specific U.S. cities or franchise markets that could see changes first.

There is one confirmed continuity point. Nation’s Restaurant News reported after Yum’s second-quarter update that Pizza Hut outside China will continue using Byte by Yum, Yum’s AI-powered technology platform, under a separate commercial agreement apart from transition services. That suggests customers may not see an immediate break in digital ordering or back-end technology even as ownership changes.

Why these two moves matter for legacy chains and their customers

The reasons behind the Wendy’s and Pizza Hut decisions are rooted in pressure on mature restaurant brands. Wendy’s second-quarter filing tied its margin strain to commodity inflation, labor rate inflation, and a decline in traffic, while Wright said in that earnings release that the chain’s turnaround will depend on translating brand equity into a proposition that fits today’s quick-service environment. Hassan’s role title itself, centered on marketing and customer growth, signals that guest demand is a central issue.

Pizza Hut’s sale followed a longer strategic review. Yum said on June 16, 2026, that its leadership team and board concluded a sale offered the strongest path to maximize shareholder value and give Pizza Hut an ownership structure better matched to its markets, competitive strengths, and long-term priorities. Yum had first disclosed in November 2025 that it was exploring strategic options for Pizza Hut.

Broader industry data helps explain the timing. Nation’s Restaurant News, citing Bank of America card data published August 25, reported that restaurant spending improved in July but chains broadly remained sluggish, with spending up 3.3% and transactions up 1.1%, while independents captured more of that momentum. For customers, that means both Wendy’s and Pizza Hut are adjusting during a period when value, traffic, and differentiation are under heavier scrutiny. The immediate result is clearer at Wendy’s than at Pizza Hut, but both companies are signaling that old operating models are no longer enough.

Dusking: The Dutch Dinner Tradition You’ve Probably Never Heard Of

Across Europe, dinner hours can signal more than taste, reflecting labor patterns, family routines, and social norms that vary sharply by country. In the Netherlands, one of the clearest examples is the longstanding habit of eating the main evening meal unusually early by Southern European or American standards. While “dusking” is not a formal Dutch culinary term confirmed by major Dutch institutions, the underlying tradition it points to — dinner commonly served around 5 p.m. to 6 p.m. — is well documented in reporting on Dutch food culture.

An early dinner remains a recognizable Dutch routine

Dutch food and culture outlet DutchReview reported in an October 7, 2025 explainer that people in the Netherlands typically eat dinner between 5 p.m. and 6 p.m., a schedule that often surprises visitors arriving from countries where the evening meal starts much later. The same publication has separately described 6 p.m. as a standard dinnertime in the Netherlands, reinforcing that the pattern is not limited to one household or one region. Those accounts do not present a national participation rate, and no official government dataset reviewed for this article assigns a verified percentage of Dutch households to the habit.

What is clear is that the early meal is treated as a broad social expectation. DutchReview’s reporting on dining etiquette and everyday customs describes dinner as a planned, time-sensitive part of the day, not an open-ended social occasion that drifts later into the night. That makes the practice visible not only in homes but also in how residents think about evening schedules.

The term “dusking,” however, appears to be a descriptive label rather than a formally recognized Dutch dining category. Available reporting supports the existence of the early-dinner custom itself, but not the idea that Dutch institutions or mainstream Dutch-language coverage widely identify it under that specific name as of September 9, 2026.

What the tradition looks like on the ground in the Netherlands

In practical terms, the Dutch pattern centers on a warm evening meal served shortly after the workday and before a longer night of socializing at home. DutchReview has reported that many Dutch households treat dinner as an efficient, regular part of domestic life, and IamExpat describes the standard Dutch dinner format as “AVG” — aardappel, vlees, groenten, or potatoes, meat, and vegetables — a shorthand that underscores how structured and familiar the meal can be.

What remains less clear is how much the schedule varies by city, age, or household type. The sources reviewed do not provide a comprehensive regional breakdown showing whether Amsterdam, Rotterdam, Utrecht, or smaller towns keep meaningfully different dinner hours. They also do not establish a nationwide trendline showing whether the custom is weakening among younger residents.

Still, multiple culture reports point to the same lived reality: guests who expect a Mediterranean-style 8 p.m. dinner may find that Dutch hosts have already eaten. That timing also shapes social etiquette, including expectations around punctuality and whether an unplanned visitor is likely to stay for the meal.

The roots are tied to work, class, and everyday efficiency

The best-documented explanation for the Dutch schedule is historical. DutchReview traces the modern pattern to 19th-century industrialization, when factory work made midday hot meals less practical for working families and shifted the warm meal toward the early evening. Its separate overview of Dutch dining traditions says lower-income households once ate their warm meal earlier in the day, while later social and economic changes pushed more families toward an evening timetable.

That account also points to 20th-century retail and household changes, including the expansion of shopping hours and middle-class routines, as factors in moving dinner toward the 5 p.m. to 6 p.m. window. More recent commentary from the same outlet links the tradition to a broader Dutch preference for efficiency and schedule discipline in everyday life.

For readers, the main takeaway is straightforward: the Dutch early-dinner custom is real, even if “dusking” is not a standard official term for it. Someone visiting or dining with Dutch households should expect the main meal to arrive earlier than in many other countries, a pattern that remains part of the Netherlands’ modern food culture according to recent reporting.

6 Burger King Items One Former Fan Says They’ll Never Order Again

Burger King still has iconic menu recognition. But brand familiarity does not guarantee a satisfying order every time.

For one former fan, the issue is not nostalgia alone. It is the growing gap between what some menu items promise and what they too often deliver.

When menu reputation stops matching the bite

A former Burger King regular can still admit the chain has marquee items that keep customers coming back. The Whopper remains the centerpiece of the brand, and Burger King’s own leadership has continued to position it as the standard-bearer for the menu. At the same time, disappointment tends to build around side items, lower-tier proteins, and desserts that feel more convenient than craveable. That disconnect is where former loyalists often draw the line.

Chicken nuggets belong near the top of that list. In June 2026, Parade reported that Burger King President Tom Curtis openly said he avoids the chain’s nuggets in their current form, adding, “We can do better, and we will.” That is an unusually blunt assessment from inside the company, and it reinforces a complaint many customers have already made about mushy texture and underwhelming flavor. When a chain executive is signaling a fix, it is fair to read that as an acknowledgment the item has not been landing.

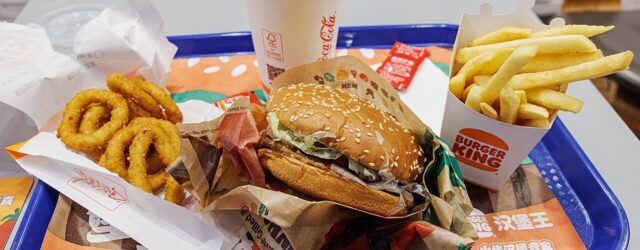
Onion Rings also divide customers more than their cult following suggests. Burger King still prominently features them on its menu lineup, but nutrition listings show a large order carries 430 calories and 770 milligrams of sodium, a heavy load for a side that can vary widely in crispness and freshness. For a former fan, that trade-off starts to feel less worthwhile when the coating is greasy or the onion center slides out in one bite.

The six items that lost this former fan for good

The first item off the reorder list is chicken nuggets, largely because even Burger King’s own president has questioned their quality. Second are Onion Rings, which can be satisfying at their best but often feel more like batter-forward filler than a sharply seasoned side. Third are Mozzarella Fries, a menu item Burger King still promotes, but one that depends almost entirely on flawless fry timing. When that timing slips, the result is rubbery cheese, limp breading, and a snack that cools down fast.

Fourth are Chicken Fries, an item that remains one of the chain’s signature alternatives to standard tenders. Their shape is memorable, but that does not always translate into a juicy, substantial bite. For some former fans, they feel engineered for dipping rather than satisfying on their own, which can make the portion seem slight for the price.

Fifth is French Toast Sticks. Burger King continues to spotlight them in its breakfast range, and official nutrition information lists 380 calories for a 5-piece order. But sweetness without much contrast can make them feel one-note, especially when they arrive soft rather than crisp-edged.

Sixth is Hershey’s Sundae Pie. It has name recognition and dessert appeal, yet it can also feel overly dense and sugary after a heavy meal. For a former fan, it is the kind of item that sounds better on the menu board than it tastes at the end of the tray.

Why former fans become selective instead of loyal

The bigger lesson is not that Burger King lacks recognizable food. It is that consistency matters more than branding once customers know the menu well. Burger King’s support materials direct guests to its Nutrition Explorer for the most up-to-date nutrition and allergen details, a sign of how carefully modern diners are weighing what they order. When an item carries high sodium, heavy breading, or a dessert-level sugar load, expectations for flavor and execution naturally rise.

That helps explain why former fans often stop short of abandoning the chain entirely. Instead, they narrow their orders to items with a stronger track record and avoid the menu sections that feel hit-or-miss. In practical terms, that usually means skipping products that rely on delicate texture, quick turnover, or reheating precision. Fried cheese, formed chicken, and sugary desserts tend to suffer most when execution slips.

For this former fan, the six-item blacklist is less about outrage than pattern recognition. A disappointing order once is forgettable. A disappointing order several times becomes a rule: never order it again.

Turns Out Your IQ Might Predict How Much You Actually Know About Wine

Wine education, beverage certifications, and consumer expertise have become increasingly visible parts of the broader food and drink business in the United States. A newly published study now argues that one ingredient behind wine knowledge may be broader cognitive ability, not just industry access or enthusiasm. The paper focuses on wine as a test case for how people build specialized knowledge in a consumer category that blends culture, commerce, and hobbyist interest.

A new wine-knowledge study puts numbers behind the link

The study, titled Bright People Know More About Wine, was accepted on July 24, 2026, and published last month in Intelligence & Cognitive Abilities. According to the journal article, researcher Maximilian Krolo examined data from 525 participants who completed a standardized wine-knowledge assessment adapted from the Wine & Spirit Education Trust Level 2 curriculum, along with a brief general-intelligence measure known as ICAR. The core result was a statistically significant relationship between higher IQ scores and higher wine-knowledge scores.

The article reported that intelligence significantly predicted wine knowledge, with a beta coefficient of 0.31 and a p-value below .001. According to the paper, that relationship remained in place even after controlling for occupational exposure to wine, meaning the effect did not disappear simply because some respondents worked around wine professionally. The study also found a significant interaction between IQ and wine-related job exposure, with a beta of 0.14 and a p-value of .005.

That means people with higher measured intelligence tended to score better on wine knowledge, and that relationship grew stronger when participants also had structured exposure through work. The paper said personal wine consumption predicted knowledge on its own, but unlike professional exposure, it did not significantly interact with IQ. In practical terms, drinking wine more often was associated with knowing more, but it was not enough to explain the full intelligence effect the researchers observed.

What the findings do and do not say for U.S. wine consumers

For U.S. readers, the immediate takeaway is not that IQ determines taste, palate, or whether someone chooses an expensive bottle over a cheaper one. The study measured declarative knowledge about wine, including taxonomy, geography, production, and styles, rather than sensory performance at a tasting table. The article also did not identify a U.S. state-by-state consumer impact, and the researcher did not release any geographic breakdown showing whether participants came disproportionately from any single market.

That matters because wine knowledge in the United States is often shaped by local conditions, including restaurant culture, retail training, and access to classes in major metro areas. But this paper did not provide city-level or state-level findings that would allow a direct comparison between markets such as New York, California, Texas, or Illinois. It also did not establish that people with higher IQs buy better wine, spend more on wine, or enjoy wine more than other consumers.

Instead, what is confirmed is narrower and more specific. According to the study, general intelligence appears to help explain who accumulates deeper factual knowledge in a specialized consumer domain, even where there is limited formal reward. For food-and-drink businesses, that distinction matters because education programs, staff training, and certification tracks are built around knowledge acquisition, not just preference.

Why wine was chosen, and what it could mean for the trade

The researcher framed wine as a useful test case because it sits outside standard academic learning while still demanding structured study. According to the paper, wine knowledge draws on classification, memorization, and integration of information about grape varieties, wine regions, production methods, and style differences. The study argued that this made wine a strong real-world example for testing whether intelligence predicts “deep” domain knowledge beyond school or workplace basics.

The article tied its explanation to long-running intelligence theories, including Raymond Cattell’s distinction between fluid and crystallized intelligence and Arthur Jensen’s argument that general intelligence helps drive knowledge accumulation. According to the paper, the findings support the idea that IQ functions as a domain-general learning capacity, not merely a proxy for schooling or social advantage. The author also said the results did not support an “experience-producing drive” explanation strongly enough to replace a learning-efficiency account.

For consumers and the wine trade, the practical meaning is measured. The paper does not say wine expertise is innate, fixed, or limited to a particular class of drinker. It says that when people are exposed to wine information, some appear better able to absorb and organize it, especially in structured settings such as hospitality, retail, or certification programs. The study concludes that intelligence may help explain who builds durable wine knowledge over time, while leaving open whether the same pattern appears in other hobbyist categories.