Top CEOs From Kraft, McDonald’s, and Whirlpool Are All Sounding the Same Alarm About Grocery Budgets

American consumer spending has held up longer than many economists expected, but major household brands are now describing sharper signs of budget stress. In recent public comments and earnings discussions, leaders at Kraft Heinz, McDonald’s and Whirlpool all pointed to the same problem: shoppers are becoming more selective about basic purchases, including food consumed at home and away from home. Their remarks do not describe a single recall, closure or state-specific event, but they do offer a broad warning about how stretched grocery and household budgets remain across the U.S.

Kraft Heinz, McDonald’s and Whirlpool are all flagging the same consumer pullback

The clearest warning came from Kraft Heinz CEO Steve Cahillane in early May 2026. According to Axios, which cited his interview comments, Cahillane said lower-income consumers are “literally running out of money at the end of the month,” a blunt assessment from the company behind Heinz ketchup, Kraft macaroni and cheese and other pantry staples. The Wall Street Journal also reported that Kraft Heinz has been emphasizing value, including lower prices on some items, more promotions and smaller package sizes at lower price points.

McDonald’s delivered a similar message on May 7, 2026, during its first-quarter earnings discussion. The Associated Press reported that CEO Chris Kempczinski said higher gas prices would disproportionately affect low-income consumers, while company leadership also described consumer sentiment as marked by heightened anxiety. Axios separately reported that Kempczinski said lower-income consumers were still pulling back and that the broader environment might be getting worse.

Whirlpool’s warning came through its earnings commentary on consumer demand. In the company’s second-quarter earnings transcript, Whirlpool said elevated interest rates, trade policy uncertainty and weaker consumer sentiment were hurting industry demand. While Whirlpool sells appliances rather than groceries, its results are often watched as a read on middle-income household finances because big-ticket purchases are among the first items families delay when budgets tighten.

The impact is national, but companies have not tied the warning to a list of states or cities

For readers looking for a state-by-state breakdown, that information is not available from the companies’ recent comments. Kraft Heinz, McDonald’s and Whirlpool have all described broad pressure on U.S. consumers, but none of the cited reports released a comprehensive list of specific cities, counties or states where households are under the greatest strain. That means the warning is national in scope, not a localized chain update or a market-specific announcement.

What is confirmed is that the pressure spans both grocery aisles and restaurant spending. Kraft Heinz is talking about consumers making trade-down decisions inside supermarkets, while McDonald’s is talking about diners who remain highly sensitive to value pricing. Whirlpool’s comments suggest the same households are also postponing durable-goods purchases, reinforcing the idea that food budgets are being managed alongside other essential expenses.

The overlap matters because these are three very different businesses. When a packaged-food company, a fast-food chain and a home-appliance maker are all describing the same consumer caution, it signals a spending pattern that reaches well beyond one category. Still, the companies have not published local maps or state-level consumer stress data tied to these remarks.

Inflation has cooled from its peak, but food costs and other essentials are still pressuring households

Recent federal inflation data helps explain why these executives are using similar language. The U.S. Bureau of Labor Statistics said the food-at-home index in July 2026 was up 2.7% from a year earlier, while the South region’s grocery index was up 2.3% over the same period. Those figures are far below the sharpest pandemic-era increases, but they still reflect higher ongoing costs for shoppers who have already absorbed years of price increases.

At the same time, restaurant and fuel costs continue to shape consumer behavior. The Associated Press reported in May that McDonald’s specifically warned higher gas prices could dent demand, especially among lower-income customers. AP also reported in June that executives across major retailers and restaurant chains were still seeing cutbacks by lower-income consumers as refunds faded and families contended with more expensive food, clothing, insurance and other bills.

For customers, that means companies are increasingly focused on value messaging rather than assuming spending will rebound quickly. Kraft Heinz has been using promotions and smaller packs to meet tighter budgets, while McDonald’s has continued leaning on value offers to keep lower-income diners engaged. The most practical takeaway is not that one region is being singled out, but that large national brands are adjusting to a consumer who is still watching every dollar of the household food budget.
Arizona’s Water Crisis Is Quietly Reaching Into Your Salad Bowl

The Colorado River is entering a new round of federally ordered cuts just as U.S. food supply chains remain heavily dependent on desert irrigation in the Southwest. In Arizona, that matters most in Yuma County, where winter lettuce and leafy greens production connects water policy directly to grocery coolers and restaurant salads nationwide. The immediate issue is not a recall or a store shelf shortage, but a verified water decision that growers and state officials say adds pressure to one of the country’s most important produce regions.

Federal cuts are now official, and Yuma agriculture is in the frame

On August 21, 2026, the U.S. Department of the Interior signed the 2027-2028 Operating Guidelines and Record of Decision for post-2026 Colorado River operations, according to Arizona Water Company’s summary of the federal action and reporting from the Associated Press. The finalized plan requires California, Nevada and Arizona to collectively reduce water use by 1.25 million acre-feet annually during the two-year period, with the possibility of deeper cuts depending on hydrologic conditions, the AP reported.

Arizona is carrying a large share of that burden. Arizona Water Company, citing state water officials, said the mandatory reductions equal roughly a 27% cut to Arizona’s total Central Arizona Project supply. Arizona’s water leaders have been warning for months that post-2026 operating rules could seriously affect the state’s Colorado River deliveries, especially supplies moved through CAP, according to the Arizona Department of Water Resources.

That does not mean Yuma lettuce fields are shutting off this season. The AP reported on August 29 that Yuma growers with high-priority rights may avoid direct cuts to their Colorado River supply over the next two years. But the same report said growers are still facing longer-term uncertainty, and that uncertainty now sits over a region central to winter salad production.

Arizona’s local produce economy is exposed, even without a confirmed field-by-field loss list

Yuma’s importance is measurable. The AP reported that the region produces about 90% of the leafy greens eaten in North America during the winter. USDA’s Economic Research Service has similarly said that from mid-November through early April, most lettuce sold in the United States comes from the irrigated desert valleys of Southern California’s Imperial County and the Yuma area of Arizona.

State production data shows how large Arizona’s lettuce footprint remains. USDA’s National Agricultural Statistics Service said Arizona harvested 64,200 acres of lettuce in 2024, and its 2025 state agriculture overview listed 24,700 acres of romaine lettuce alone, with production valued at about $525.8 million. The Arizona Department of Agriculture also reported that iceberg lettuce accounted for 85% of total assessed shipments in the most recent annual period posted by the agency.

What is not yet known is whether any specific Yuma-area farms will alter acreage, crop mix or planting schedules as a direct result of the August federal action. No state agency has released a field-level list of expected reductions tied specifically to winter lettuce production in Yuma County. For consumers, the confirmed fact is that one of the nation’s most important salad-growing regions is operating under a tighter water framework than before.

The pressure comes from long-term river decline, not a single bad growing season

The cause is broader than one drought year. The Arizona Department of Water Resources said in February that all five federal alternatives for post-2026 river operations would seriously affect Arizona supplies, after negotiations among basin states broke down ahead of a federal deadline. The dispute centers on how to manage a river system under persistent drought, declining reservoir levels and competing claims from cities, tribes and agriculture.

Researchers and extension specialists have also documented the agricultural side of that pressure. University of Arizona Cooperative Extension said declining freshwater quantity and quality in Yuma County pose complex challenges for sustainable agriculture, while another 2026 extension publication said irrigation, not rainfall, is the defining water supply issue for Yuma Valley production. USDA Agricultural Research Service materials likewise describe winter vegetables, including lettuce, as a significant consumptive use of water in the Lower Colorado River Basin.

For shoppers and restaurant operators, the practical takeaway is narrower than the headline. There is no confirmed federal finding that Arizona lettuce will disappear from stores, and no agency has published a consumer advisory on leafy greens tied to the August water ruling. What is confirmed is that the farms supplying a major share of winter salads are entering the next growing cycle under stricter Colorado River rules and continued uncertainty about how much deeper future cuts could go.

Meet the World’s Oldest Scotch Whisky, an 88-Year-Old Single Malt From The Balvenie

The_Balvenie

Rare and ultra-aged spirits remain a small but closely watched corner of the global drinks business, where distilleries use limited releases to reinforce brand identity and pricing power. That trend now runs through Speyside, Scotland, where The Balvenie has introduced an 88-year-old single malt tied to a new 1931 Collection. The release places one of Scotch whisky’s most tradition-focused producers at the center of a record-setting launch.

The release sets a new age record for Scotch

The Balvenie has unveiled an 88-year-old single malt that the company’s trade coverage says is the oldest single malt Scotch whisky ever released, surpassing the 85-year-old Glenlivet-distilled expression issued by Gordon & MacPhail in 2025, according to Whisky Magazine and other spirits publications. The whisky was drawn from Cask 239, filled on March 5, 1931, and bottled in 2019, with the public unveiling taking place on September 1, 2026, in connection with Frieze Seoul programming. Only 17 bottles were produced, according to Wallpaper and additional trade reports.

The release is the centerpiece of The Balvenie’s new 1931 Collection, which also includes 15-year-old and 12-year-old companion whiskies, according to coverage from Whisky Magazine, AOL and Beverage B2B. Those reports said the related releases were built to connect the record-setting bottle to The Balvenie’s production history, including its floor malting tradition and estate-grown barley program. The company has not publicly disclosed a retail price for the 88-year-old edition, and several reports said it is being reserved for private clients and collectors rather than broad retail distribution.

The local impact centers on Speyside and a Seoul debut

The confirmed geography in this story begins in Dufftown, Speyside, where The Balvenie is produced by The Balvenie Distillery Company Limited, part of William Grant & Sons. William Grant & Sons states that The Balvenie opened five years after Glenfiddich, placing the distillery’s roots in the late 19th century, while the 1931 fill date underscores how long casks can remain under careful warehouse supervision before release. For Scotland’s whisky sector, the launch adds another headline-grabbing ultra-aged bottling tied directly to Speyside’s reputation for collectible single malt.

The public-facing debut, however, is not happening first in Scotland or the United States. Reporting from Frieze and related art and culture coverage shows The Balvenie partnered with Frieze Seoul, whose 2026 edition runs September 2 through September 5 at COEX in Gangnam, Seoul, with the whisky collection unveiled through a September 1 immersive event tied to artist Daniel Arsham. The company has not released a full market-by-market allocation for the 17 bottles, and it has not announced any general U.S. retail rollout for the 88-year-old expression.

The broader context is luxury scarcity and brand storytelling

The immediate reason this launch matters is scarcity. Spirits coverage consistently framed the bottle as a record-setting release at a time when top Scotch makers and bottlers are using extreme age statements, single-cask provenance, and art-world collaborations to differentiate themselves in the luxury market. Whisky Magazine specifically noted that The Balvenie’s 88-year-old overtook Gordon & MacPhail’s 85-year-old Glenlivet from 2025, while multiple outlets described the new bottle as part of a broader collector-focused strategy rather than a mainstream shelf product.

For consumers, that means this is better understood as a prestige release than a bottle likely to appear at a neighborhood liquor store. The Balvenie’s own U.S. storefront currently highlights its regular range, but no public sales listing for the 88-year-old release appears there, reinforcing reports that access is limited. What customers are most likely to see in the near term is the halo effect: renewed attention on The Balvenie’s more widely available lineup, and more luxury Scotch launches that use archival stock, historic production dates, and tightly controlled bottle counts to generate demand.

SNAP Cuts Are Quietly Reshaping How Americans Shop for Groceries

The changes rarely announce themselves in a dramatic way. They show up instead in smaller carts, more store-brand staples, and tougher choices in the meat aisle.

For many households, SNAP cuts are not just shrinking food budgets. They are changing the rhythm of grocery shopping itself.

Smaller benefits, sharper trade-offs

SNAP remains one of the country’s largest anti-hunger programs, serving an average of about 42 million people a month in recent years. USDA data show 41.7 million people received benefits on average each month in fiscal year 2024, or 12.3 percent of U.S. residents, underscoring how deeply the program shapes food buying across the country. The average SNAP household received a monthly benefit of $332 in fiscal year 2023, according to USDA program characteristics data, which means even modest policy changes can quickly alter what lands in the cart.

Those changes are now becoming more visible. The July 2025 budget law known as the One Big Beautiful Bill Act set in motion major SNAP reductions through expanded work requirements, state cost-sharing, and a re-evaluation of the Thrifty Food Plan, the formula used to set benefits. Urban Institute researchers estimate 22.3 million families could lose some or all SNAP support as those provisions take effect. Even before full implementation, analysts have warned the law would widen the gap between benefits and the real cost of food.

That gap matters because grocery inflation has cooled, but it has not disappeared. USDA’s Economic Research Service said food-at-home prices in May 2026 were still 2.7 percent higher than a year earlier, with especially sharp pressure in beef and veal, fresh vegetables, sugar and sweets, and nonalcoholic beverages. For a household already shopping on a fixed EBT balance, that kind of category-level inflation pushes spending away from fresh produce and protein and toward cheaper, shelf-stable calories.

The grocery cart is changing first

When benefits tighten, shoppers usually do not stop shopping. They downgrade. USDA research found SNAP households spent about $544 more on food at home in 2022 than non-SNAP households in the lowest income quartile, a sign that benefits directly support grocery purchasing power rather than merely offsetting existing spending.

The first adjustment is often product choice. Families stretch dollars by swapping fresh meat for processed proteins, shifting from national brands to private label, and buying fewer convenience foods even when those products save time for working parents. A healthy basket becomes harder to maintain when benefit levels lag local prices, especially in urban counties where earlier Urban Institute work found modestly priced meals still cost more than maximum SNAP support could reliably cover.

The second adjustment is store choice. Households become more promotional, splitting trips across discount grocers, dollar stores, warehouse clubs, and supermarkets to chase price gaps item by item. New USDA retailer stocking rules and state-level waiver activity around restricting soda and candy purchases may also gradually influence merchandising and checkout behavior, especially in stores with heavy SNAP traffic. The result is a more strategic, more fragmented shopping pattern centered on stretch, substitution, and timing.

Beyond the checkout lane

The effects do not end with what families buy. They spill into when people shop, how often they shop, and whether they can avoid debt while doing it. Urban Institute survey work found nearly 1 in 4 adults reported difficulty affording adequate food in 2025, and separate Urban research found more families were relying on credit cards and savings to cover groceries.

That changes household behavior in practical ways. More shoppers wait for benefit issuance dates, buy in bulk early in the month, and rely on pantries later in the cycle when funds run low. Urban researchers reported charitable food participation remained elevated in 2025, with nearly 1 in 6 adults using charitable food assistance, suggesting the private food network is increasingly being asked to absorb pressure created by public benefit reductions.

There is also a broader market effect. SNAP dollars are spent quickly, so when benefits weaken, neighborhood grocers, mass retailers, and food manufacturers all feel it. The quiet reshaping of American grocery shopping is therefore bigger than any single household budget. It is a shift in national food demand, visible in the rise of cheaper substitutes, the squeeze on nutritious staples, and the growing normalization of shopping with calculators, coupons, and contingency plans.

Millions Take This Supplement for Bone Health. New Research Says It May Not Work

For years, calcium and vitamin D supplements have been a standard part of bone-health advice for older adults across the U.S. Now a major new evidence review published in The BMJ is challenging that routine guidance for most people taking them to prevent fractures and falls. The findings do not apply to every patient group, but they add to growing scrutiny of supplements that remain widely used.

The review found little benefit in a large analysis

The specific action was a systematic review and meta-analysis published in The BMJ on May 20, 2026. Researchers analyzed 69 randomized clinical trials covering 153,902 adults and concluded that calcium supplements, vitamin D supplements, or both together provided little to no clinically meaningful benefit for preventing overall fractures or falls in most older adults, according to the journal and the study authors.

The review found moderate-certainty evidence from 11 trials involving 9,067 participants for calcium alone, high-certainty evidence from 36 trials involving 92,045 participants for vitamin D alone, and high-certainty evidence from 15 trials involving 51,126 participants for combined supplementation. Across those comparisons, the researchers reported little to no reduction in overall fracture risk. They also found little to no benefit for hip fractures and for falls, based largely on moderate- to high-certainty evidence.

The paper was led by researchers in Canada, including authors affiliated with institutions in Quebec and Alberta, and it set thresholds for what would count as a clinically meaningful benefit before interpreting the results. That matters because the authors said small statistical differences do not necessarily translate into meaningful changes for patients in everyday care. Their conclusion was direct: the available evidence does not support routine supplementation with calcium or vitamin D, alone or together, to prevent fractures and falls.

What the findings could mean in the U.S.

The review is broad rather than state-specific, and it speaks to a national U.S. health habit rather than a localized recall, closure, or policy change. What is confirmed is that supplements commonly sold and recommended for bone health remain widely used, while this new analysis suggests the routine practice may not deliver the expected protection against fractures and falls for most older adults. What is not yet known is how quickly U.S. clinical guidelines, health systems, or individual physicians may change their recommendations in response.

That uncertainty matters because supplement use is deeply embedded in routine care. The ScienceDaily summary of the BMJ paper said vitamin D supplements, with or without calcium, continue to be widely recommended by healthcare providers, professional guidelines, and regulatory agencies, even as earlier reviews had already raised doubts. In practical terms, many Americans may continue hearing advice that this latest review says deserves re-evaluation.

The paper also included limits that are important for U.S. readers. The authors said some parts of the analysis included relatively few studies and participants, and they cautioned that the results may not apply to people with certain bone disorders or to patients already receiving medication for osteoporosis. That means the findings are strongest as a challenge to routine use in the general older-adult population, not as a universal rule for every patient.

Why researchers say the focus may need to shift

The context behind the study is straightforward: falls are common, fractures are costly, and healthcare systems want low-cost prevention tools that can be used at scale. In the linked BMJ editorial, the journal noted that about 30% of adults age 65 and older experience falls at least annually, and more than half of nursing-home residents do as well. Because fractures can lead to pain, disability, hospitalization, and long-term care needs, supplements have remained attractive as an easy intervention.

But the review adds to a body of research suggesting that attraction has outpaced proof. The authors said earlier studies had already shown no fracture-risk reduction for calcium alone or vitamin D alone, while results for taking both together were mixed. In this new analysis, the findings remained broadly consistent even after accounting for age, sex, previous fractures, previous falls, and average calcium intake from food.

The linked editorial and related commentary pointed toward other interventions with stronger evidence. According to the ScienceDaily summary of the BMJ research, those include balance training, resistance exercise, and personalized fall-prevention programs that combine exercise, hazard assessment, and education based on individual risk factors. For patients and clinicians, the immediate takeaway is not that bone health no longer matters, but that routine supplement use alone may not offer the protection many people assumed it did.

Researchers Reviewed 350+ Studies on Protein. What They Found May Surprise You

Protein has become one of the food industry’s biggest selling points, showing up in everything from snack bars to cereal and bottled drinks. A new review published July 31 by researchers at the University of Wisconsin-Madison takes direct aim at that trend, arguing that for many sedentary adults, the evidence does not support the idea that more protein is always better. The paper stops short of changing dietary guidance, but it adds new scrutiny to one of the fastest-growing nutrition messages in the marketplace.

A major review questions whether more protein is necessary for most adults

The review, titled The hallmarks of protein and amino acid restriction in aging and longevity, was published July 31 and synthesized findings from more than 350 published papers, according to a University of Wisconsin-Madison news release and coverage by Medical Daily. The authors, including Bailey Knopf and corresponding author Dudley Lamming, examined evidence from yeast, fruit flies, rodents, and human clinical trials rather than conducting a new experiment. That distinction matters because reviews identify patterns across existing research, but they do not prove cause and effect in the same way a long-term randomized human trial can.

According to the review summary, the authors found recurring links between lower protein intake and improved metabolic health, changes in nutrient-sensing pathways, reduced cellular senescence, improved mitochondrial function, and markers associated with healthier aging. In human trials included in the review, protein restriction was associated with weight loss, lower fat mass, and reduced fasting blood glucose without requiring overall calorie restriction, as Medical Daily reported. The researchers said those human findings are the most directly relevant to everyday nutrition decisions, even though much of the mechanistic evidence still comes from animal and cell research.

A central part of the paper’s argument involves fibroblast growth factor 21, or FGF21, a hormone that rises when protein intake falls. The review said higher FGF21 is associated with increased energy expenditure, better blood sugar control, and lower inflammation, while earlier animal research cited by the University of Wisconsin-Madison found longevity benefits in mice with elevated FGF21. The authors also highlighted specific amino acids, especially branched-chain amino acids such as isoleucine and valine, along with methionine, suggesting that protein composition may matter as much as total quantity.

The findings are most relevant to sedentary adults, not every consumer buying protein products

The clearest practical message in the review is that the findings are aimed largely at sedentary adults rather than the public as a whole. Lamming said in the university release that many people are likely consuming more protein than they actually need, tying that conclusion to low activity levels rather than to all adults. That is an important distinction at a time when protein-fortified foods are widely marketed to mainstream shoppers, including people who are not regularly doing resistance training or endurance exercise.

The review also points back to existing baseline guidance. Medical Daily noted that the recommended dietary allowance for adults remains about 0.8 grams of protein per kilogram of body weight per day, with the underlying estimated average requirement near 0.66 grams per kilogram. Popular targets promoted in fitness culture and food marketing often run above those levels, but the new review does not say everyone should cut back. Instead, it questions whether extra protein in routine packaged foods solves a real nutritional problem for most people eating a varied diet.

The researchers were equally clear about who falls outside that broad takeaway. The review said athletes and consistently active adults use amino acids directly for muscle remodeling, which may reduce the metabolic concerns raised for sedentary adults. It also said the findings should not be generalized to older adults, pregnant or breastfeeding people, people recovering from illness or surgery, or those with kidney disease or a history of disordered eating, because those groups may have different clinical protein needs.

Why the review matters now for shoppers, food companies, and future nutrition guidance

The timing of the review matters because protein has evolved from a nutrient into a retail category. Grocery shelves now include protein coffee, protein water, protein cereal, and snack products built around the idea that added protein automatically improves a food’s value. The University of Wisconsin-Madison team and Medical Daily both framed the new review as a challenge to that assumption, especially for consumers whose daily routines are largely sedentary and who may already meet standard protein needs through regular meals.

At the same time, the paper leaves major questions unresolved. The review did not show that lowering protein extends human lifespan, and the authors did not claim it did. Medical Daily reported that no long-duration randomized human trials currently show whether the metabolic changes seen in shorter studies translate into better health outcomes over decades, which means the strongest evidence for longevity still comes from animal models rather than people.

For consumers, the immediate implication is narrower than many headlines suggest. The review supports skepticism toward the blanket message that more protein is better for everyone, but it does not amount to a universal recommendation to eat less protein. For now, the most factual takeaway is that protein needs still vary by age, activity level, and health status, and this July 31 review adds evidence that for many sedentary adults, the current protein boom may be overshooting what their bodies actually require.

Just 5 Companies Now Control Nearly Half of U.S. Grocery Sales. Guess Who’s on Top.

The American grocery aisle looks crowded, but the business behind it is getting more concentrated. A handful of retailers now wield enormous power over what people buy, what brands get shelf space, and how prices are set.

That concentration starts with one company that has turned food shopping into a scale game few rivals can match.

Walmart Still Sits Firmly at the Top

Walmart remains the undisputed leader in U.S. grocery sales, and the gap is not especially close. Recent industry reporting from Supermarket News puts Walmart at about 19.9% of the U.S. grocery market in 2026, while other market trackers and analysts often place its share even higher depending on how they define grocery and whether club, mass, and digital sales are included. However measured, Walmart is the clear No. 1.

What matters more than the exact decimal point is the structural advantage. Walmart combines supercenters, neighborhood markets, aggressive private-label pricing, and a logistics machine built for national scale. Its annual filings also show a business large enough to keep investing in automation, delivery, and store remodels even when margins are thin. In grocery, volume is leverage, and Walmart has more of it than anyone else.

That scale affects the entire food chain. Suppliers want access to Walmart’s shelves, but they also face intense pressure on pricing, packaging, and promotions. For shoppers, the upside is convenience and broad price competitiveness. The downside is that when one retailer becomes the default food store for millions of households, its decisions ripple across the market.

The Rest of the Big Five Are Fighting for Position

Behind Walmart, the next tier is made up of chains that look very different from one another but share one goal: hold onto food dollars in a brutally competitive market. Kroger remains one of the country’s biggest conventional grocers, while Costco has become a food powerhouse by pairing low markups with high-volume bulk buying. Albertsons stays relevant through a sprawling banner strategy that includes Safeway, Jewel-Osco, and others, while Ahold Delhaize USA competes through chains such as Food Lion, Giant, Hannaford, and Stop & Shop.

Taken together, these five companies account for roughly 40% to nearly 50% of U.S. grocery spending, depending on the source and methodology. Some analyses put the combined figure a little below that threshold, while others place it above it once broader definitions of grocery retail are used. The larger point is consistent: a very small group controls an enormous share of the nation’s food purchases.

Even so, this is not a static leaderboard. Costco continues to gain ground with affluent and middle-income shoppers alike, and discount players such as Aldi keep pressuring the traditional supermarket model. According to NRF rankings and company filings, each major player is still investing heavily in store growth, digital fulfillment, and own-brand assortments to defend share.

Why This Matters for Prices, Choice, and Competition

For consumers, consolidation is a mixed story. Big retailers can use purchasing power and supply-chain efficiency to hold down prices on staples, and that matters in a country where USDA data show food-at-home prices were still higher in 2025 than in 2024. At the same time, concentration can reduce local competition, especially in areas where one or two chains dominate the weekly grocery run.

For smaller grocers, the challenge is even sharper. Independents and regional operators often cannot match the advertising budgets, delivery infrastructure, or supplier terms available to national chains. That is one reason antitrust scrutiny remains intense. The FTC’s successful challenge to the proposed Kroger-Albertsons merger in December 2024 underscored how seriously regulators view further consolidation in food retail.

The next phase of the grocery fight will be shaped by more than store count. It will hinge on digital loyalty programs, private-label expansion, prepared foods, and faster fulfillment. But the central fact is already clear: American grocery shopping may feel local, yet the market is increasingly controlled by a few corporate giants, and Walmart still stands tallest.

Stanford Researchers Built an AI to Judge Burgers! The Results Are Wild

Artificial intelligence is moving deeper into the food business as companies and universities test whether algorithms can speed up product development and help balance taste, nutrition, and sustainability. At Stanford University, researchers used that approach on one of the country’s most familiar foods: the burger. Their results, published in late June, turned a Bay Area restaurant tasting into an unusually concrete test of whether an AI system can make food people actually want to eat.

Stanford’s BurgerAI moved from recipe data to a real-world taste test

Stanford researchers announced on June 26 that they had developed BurgerAI, a generative system designed to create burger recipes optimized for taste, health, and environmental performance, according to Stanford Report and the peer-reviewed paper published in npj Science of Food. The team reported training the system on 2,216 recipes using 146 ingredients, then using the model to search a recipe space it estimated at more than 10 to the 44th possible combinations. That scale matters because the project was presented not as a novelty image generator, but as a tool for structured food design.

The researchers then took the project beyond simulation. Stanford said five professionally prepared, AI-designed burgers were served in a blinded tasting at a San Francisco restaurant to more than 100 diners, while the paper lists 101 participants in the sensory evaluation. In the published results, the system’s “delicious” burgers scored the same or better than a Big Mac reference in overall liking, flavor, and texture, according to the paper and Stanford’s summary of the findings.

The study also said BurgerAI could rediscover a classic burger pattern without being directly told to copy it. In the paper, the model was described as able to reproduce a recipe resembling the Big Mac without explicit supervision, while also generating newer combinations that rated highly with tasters. Stanford researchers including Ellen Kuhl, Vahidullah Tac, and Christopher Gardner were named on the work.

The Bay Area connection is clear, but the local rollout is not

For local readers, the most direct Bay Area tie is the live tasting itself. Stanford said the blinded test was conducted at a San Francisco restaurant, making the region the first public proving ground for the burger experiment rather than just the home base of the university. That gives the study a concrete local footprint, even though BurgerAI is still a research project rather than a consumer product or restaurant launch.

What is confirmed is that Bay Area diners were part of the evaluation process and that Stanford framed the work as a practical food-design tool with possible commercial applications. What is not yet known is whether any restaurant, food manufacturer, or Stanford-affiliated dining program plans to put BurgerAI-designed burgers on a permanent menu. Stanford has not announced a retail rollout, licensing agreement, or a list of specific California restaurants that may test the recipes next.

The local significance also comes from geography and industry overlap. Stanford sits at the intersection of Silicon Valley computing research and California food innovation, where universities, startups, and large consumer brands regularly collaborate on new product development. In that context, the burger project reads less like a one-off stunt and more like an early-stage demonstration of how AI could be used in menu development and alternative-protein formulation.

Researchers say the bigger goal is faster food design with measurable tradeoffs

The Stanford team said the project was built to address a long-standing problem in food development: improving one trait, such as taste, can make it harder to improve another, such as nutrition or environmental impact. In Stanford’s account and the npj Science of Food paper, the researchers described BurgerAI as a way to navigate those tradeoffs systematically instead of relying only on slow cycles of kitchen testing, consumer panels, and reformulation. The burger was used as a model food because it is familiar, variable, and easy to compare across versions.

That broader context helps explain why the findings drew attention. The paper reported that one mushroom-based burger achieved an environmental impact score more than an order of magnitude lower than the Big Mac benchmark, while a bean-based burger reached nearly twice the nutritional score. Those results suggest the model was not simply ranking indulgent recipes higher, but searching for combinations that could satisfy multiple goals at once.

For customers, the immediate takeaway is limited but tangible. No Stanford-designed burger has been announced for general sale, and the university has not said when or where consumers might buy one. What the study does show, based on a San Francisco tasting with 101 participants and a peer-reviewed publication, is that AI-assisted food design is moving from theory into test kitchens, with taste still treated as the deciding factor.

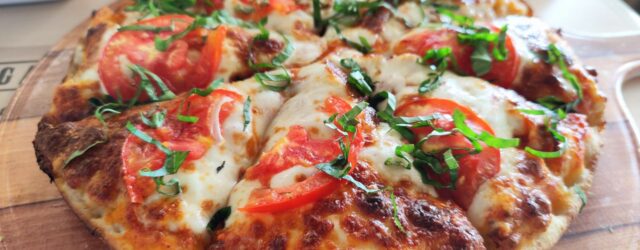
Every Region Thinks Its Pizza Is the Best! Here’s How They Actually Differ

Pizza remains one of the country’s most widely eaten foods, with USDA researchers reporting that about 11% of Americans consume pizza on any given day. Across the U.S., that popularity has produced distinct regional styles tied to local restaurant histories, immigrant communities, and even industrial equipment. What Americans call “pizza” can mean very different things depending on whether the order is placed in Manhattan, Chicago, Detroit, New Haven, or St. Louis.

New York, Chicago, and the argument over crust and structure

New York-style pizza is built for speed, portability, and scale. The defining traits are a large, round pie baked into wide slices that can be folded, a format that became closely associated with city pizzerias and grab-and-go eating. While there is no single regulatory definition of New York-style pizza, food publications and tourism materials consistently describe it as a thin-crust slice with enough structure to bend without breaking.

Chicago’s most famous counterpoint is deep-dish. Uno says it invented deep-dish pizza in downtown Chicago in 1943, and that claim has been widely repeated in mainstream food history coverage. The style differs from New York’s by reversing the eating experience: instead of a thin base supporting a light layer of toppings, deep-dish uses a taller, sturdier crust that holds cheese, toppings, and a generous layer of sauce in a pie more often eaten with a knife and fork.

Those differences are not only about thickness. New York slices prioritize stretch, chew, and quick bake service, while Chicago deep-dish emphasizes enclosure, layering, and a longer bake that produces a more casserole-like interior. The result is that the long-running New York-versus-Chicago argument is really a disagreement over what pizza is supposed to do: travel in the hand, or hold a full meal’s worth of ingredients in a pan.

Detroit, New Haven, and the role of pans, ovens, and char

Detroit-style pizza is one of the clearest examples of a city-specific method becoming a national category. Buddy’s Pizza says the style began at Buddy’s Rendezvous Pizzeria on Detroit’s east side in 1946, where Gus Guerra baked square pies in forged-steel pans borrowed from local automotive plants. The hallmarks remain a rectangular or square shape, a thicker dough, edge-to-edge cheese that caramelizes against the pan, and sauce added in stripes on top rather than under the cheese.

New Haven’s apizza follows a different logic. Yale alumni materials describe New Haven apizza as a style of its own, and local accounts have long tied it to Wooster Street’s Italian American pizzerias. The most recognizable characteristics are a thinner crust, pronounced char from a hot oven, and a drier, more blistered finish than many New York slices.

What links Detroit and New Haven is that both are highly localized styles rooted in technique. Detroit depends on the pan and the cheese edge for texture. New Haven depends on oven heat, blistering, and a deliberately well-done bake. In both cases, the local identity is not just about toppings; it is about a repeatable production method that residents recognize immediately.

St. Louis, older roots, and why regional pizza keeps multiplying

St. Louis-style pizza is defined less by height than by texture. St. Louis Magazine describes the city’s best-known version, especially through Imo’s, as a combination of Provel cheese, a crisp crust, and square slices. That makes it distinct from both the floppy New York slice and the pan-baked Detroit pie, because the goal is a cracker-like base cut into party squares rather than large wedges.

The broader context helps explain why so many cities defend their version so intensely. Smithsonian has noted that American pizza culture includes major local variations such as New Jersey tomato pies, New Haven apizza, and St. Louis pies with Provel, while USDA consumption data shows pizza remains a routine part of U.S. eating patterns. When a food is this common, local restaurants have room to define it on their own terms.

That is also why debates over the “best” style rarely get settled. Some regions prize foldability, some prize crunch, some prize char, and some prize pan structure. What changes from place to place is not just taste, but the underlying definition of what a proper slice should look like when it reaches the table.

54,000 Pounds of Rice Just Got Pulled From Shelves. Here’s the Reason Why

A pantry staple is suddenly making headlines for the wrong reason. More than 54,000 pounds of jasmine rice have been pulled from shelves, and the reason is serious enough that shoppers should take a closer look at what is sitting in their cabinets.

What was recalled, and why it was removed

The product at the center of the recall is Lundberg Family Farms White Jasmine Rice sold in 2-pound bags. Recent federal recall records show the action covers 27,324 packages, totaling 54,648 pounds of rice. Multiple news reports say the product was distributed across a dozen states, turning what first seemed like a limited issue into a much broader consumer alert.

The reason for the recall is potential contamination with foreign material. That wording matters. In food safety language, foreign material can refer to unwanted physical matter in the product, such as hard fragments, debris, or other non-food substances that do not belong in the package.

This is not the same kind of recall as one tied to Salmonella, Listeria, or an undeclared allergen. Instead, the primary concern is physical injury. According to reporting that cites the FDA’s enforcement listing, that risk can include choking, dental damage, mouth injury, or digestive irritation if contaminated rice is cooked and eaten.

The recall has also been described as a Class II event in federal records. That means the product may cause temporary or medically reversible health consequences, while the chance of severe long-term harm is considered remote. Even so, regulators treat physical contamination seriously because consumers often do not notice a problem until a product is already being prepared or eaten.

Why the recall is making news again now

One reason this story is resurfacing is timing. Several outlets reported that the rice had already been pulled from store shelves months earlier, but the FDA’s updated enforcement report brought fresh national attention to the total volume involved. In other words, this is not necessarily a brand-new recall, but a clearer federal accounting of how much product was implicated.

That detail is important for consumers because rice is a long-shelf-life pantry item. A bag bought in spring 2026 could still be unopened in late summer or early fall, especially in households that buy staples in bulk. As Medical Daily noted in its coverage, shelf-stable foods can outlast the original recall headlines, which makes follow-up reporting especially valuable.

Another reason the story gained traction is the size of the number. More than 54,000 pounds sounds dramatic, and it is. But in practical terms, the figure reflects 27,324 individual retail packages rather than loose bulk rice, which helps consumers understand the scale more clearly.

Reports have also varied slightly on whether the distribution reached 12 or 13 states. That kind of discrepancy can happen as recall databases are updated and media reports catch up. The most important takeaway is that this was not an isolated single-store issue by the time the broader details became public.

What shoppers should do if they have this rice at home

Anyone who recently bought Lundberg white jasmine rice should check the package carefully, especially if it is a 2-pound bag. Consumers should compare the product information on hand with official recall details from the FDA or the retailer where the rice was purchased. If there is a match, the safest move is not to cook or eat it.

Shoppers should also resist the temptation to simply rinse the rice and use it anyway. Washing may remove dust or loose starch, but it cannot reliably eliminate all foreign material hazards. If the contamination involves hard fragments or other embedded debris, rinsing is not a dependable safety fix.

Most recalls like this direct consumers to discard the product or return it for a refund, depending on retailer policy. If any of the rice has already been prepared and someone experiences mouth pain, choking, or digestive discomfort after eating it, medical advice should be sought promptly. Physical contamination incidents can seem minor at first, then worsen.

The larger lesson is straightforward: even basic pantry items deserve a second look when recall news breaks. Rice is one of the foods people tend to trust automatically, which is exactly why these alerts matter. A familiar product can still pose a risk when a production run goes wrong.